Historical analysis: ChainCatcher published this Glassnode report on November 11, 2026, at 23:17 UTC+8. The figures below retain the report’s original measurement dates; they are not current market readings.
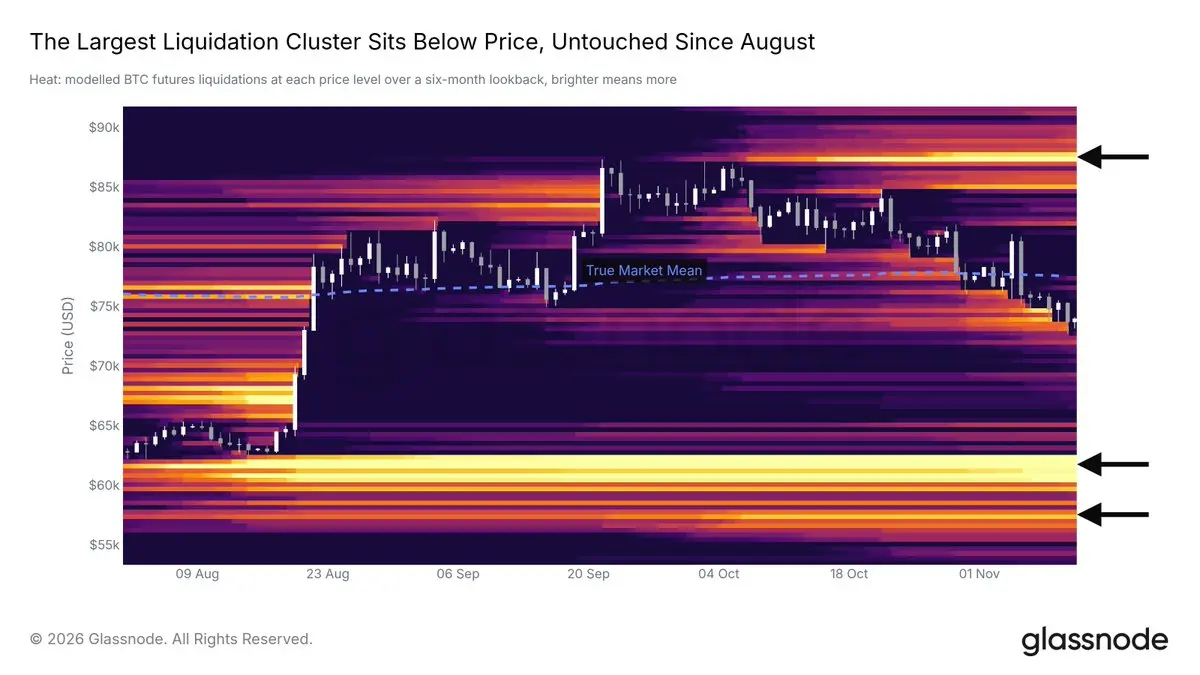
Bitcoin was trading near $74,000 in Glassnode’s November 11 assessment, below the $75,600 average cost basis of short-term holders—investors who had bought within the preceding 155 days. Glassnode’s central finding was a divergence: measures of available capital and U.S. demand were weakening, while nearby leverage had been cleared and two large-wallet cohorts had begun accumulating. Neither side of that evidence, on its own, established where the price would go next.
Recent buyers and the broader price structure
Glassnode reported that roughly 35% of short-term-holder coins remained in profit, down from nearly all of them at the September high. Sellers in that cohort were realizing a small loss on average. About two-thirds of those coins had been acquired above the prevailing price, across three purchase-price ranges extending to $83,600. Glassnode suggested that holders seeking to exit at break-even could add supply during a rebound. Its cost-basis distribution showed a concentrated block below the price at $62,000–$66,000.
The report distinguished that pressure from a break in the longer-term structure it described. September’s high was the first higher high since Bitcoin’s 2025 all-time high, and the price remained above the June low of $58,500. Glassnode identified $77,500—the True Market Mean—as a level that would put about half of short-term-holder coins back in profit if reclaimed.
Capital and U.S. demand indicators
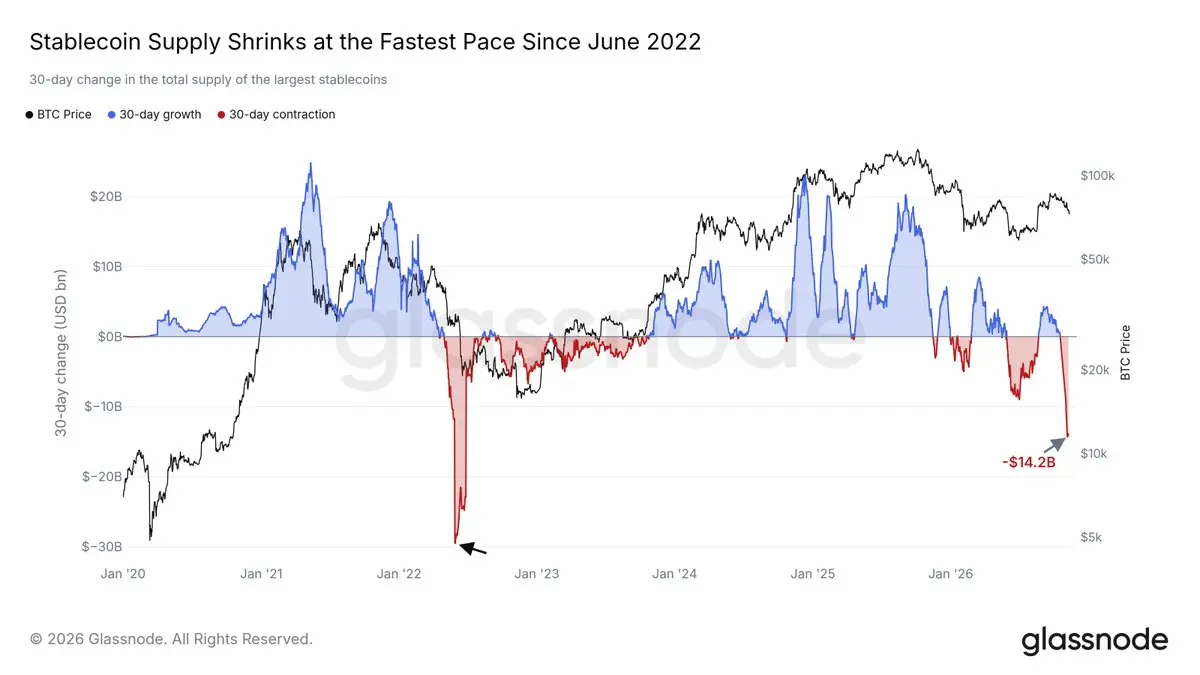
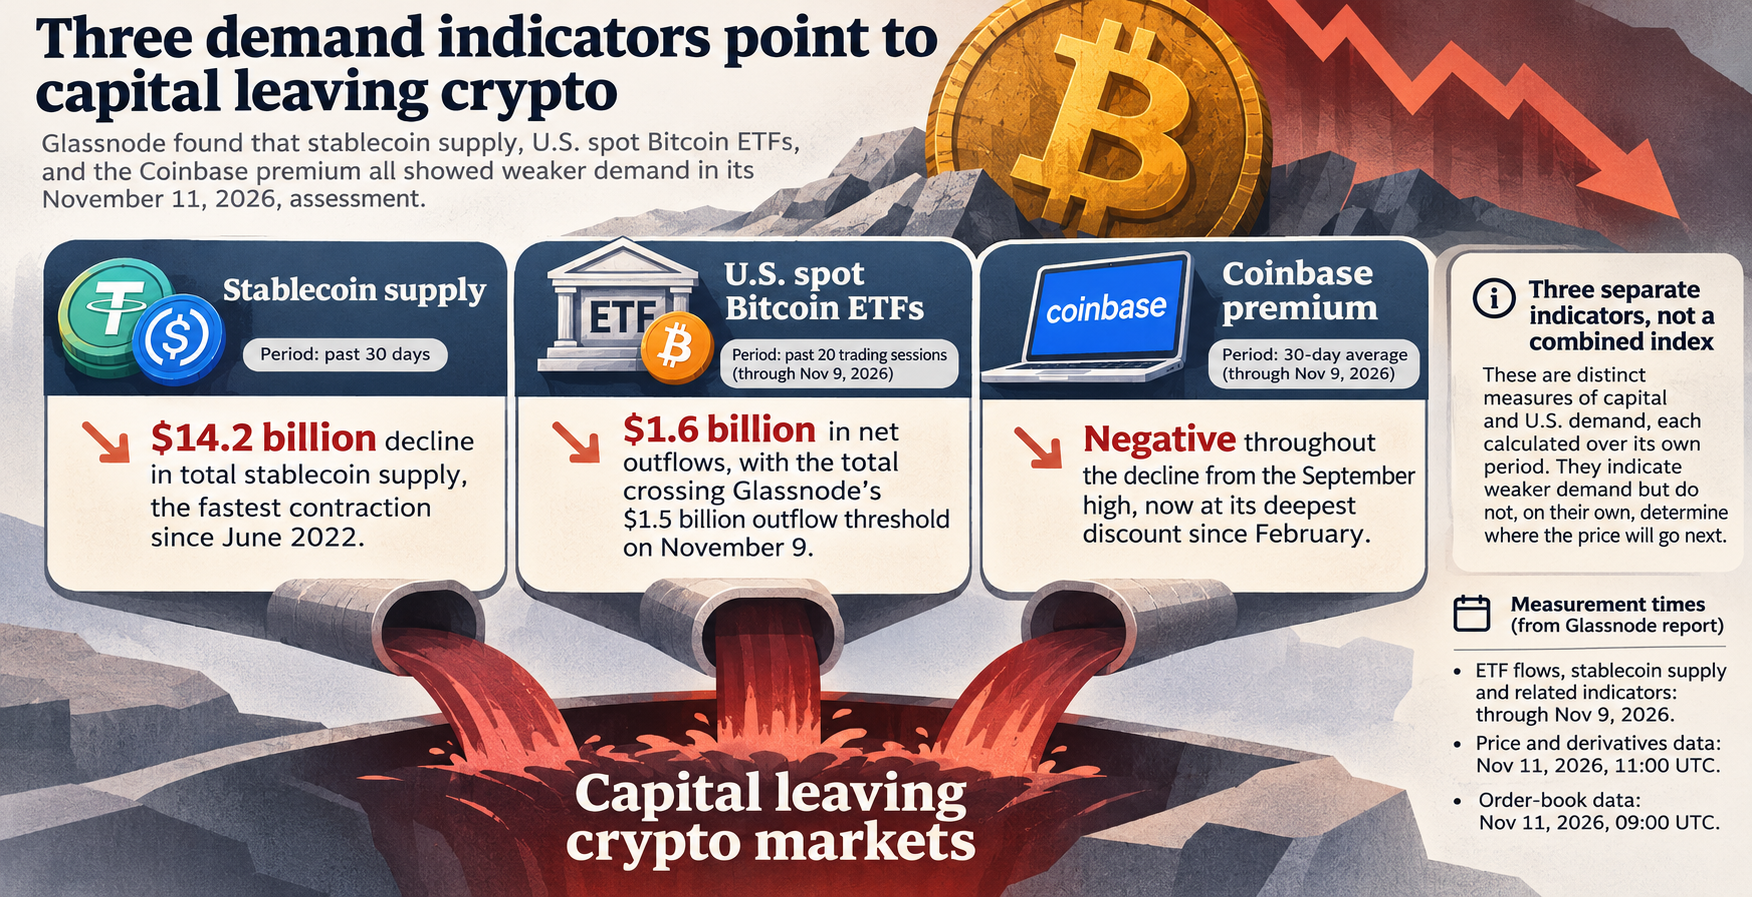
Glassnode measured a $14.2 billion decline in total stablecoin supply over the preceding 30 days, calling it the fastest contraction since June 2022. It interpreted the decline, alongside Tether trading slightly below $1, as evidence of capital leaving crypto markets. A return to growth in the 30-day supply change would be an initial sign of that measure reversing, not proof of a sustained inflow.
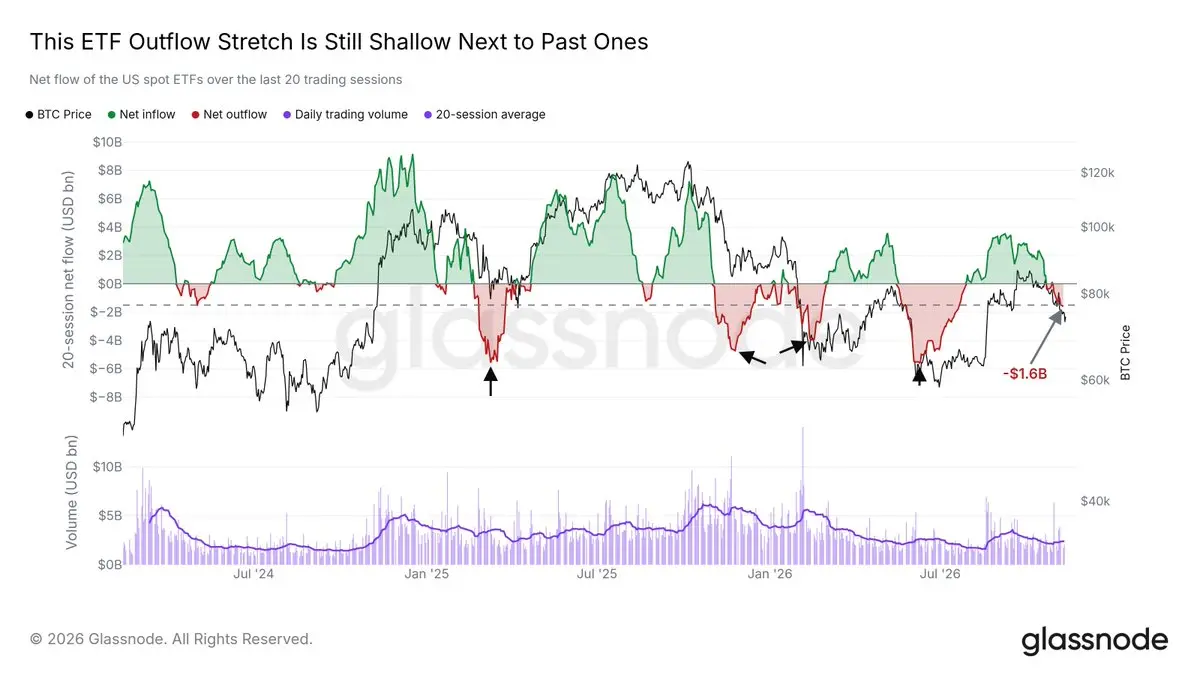
U.S. spot Bitcoin ETFs recorded $1.6 billion in net outflows over 20 trading sessions. According to Glassnode, the total crossed its $1.5 billion threshold for defining an outflow period on November 9; it also characterized this episode as shallower than most earlier ones. The report said ETF inflows in previous episodes resumed only after Bitcoin had made a low, making their return a retrospective confirmation rather than an advance signal.
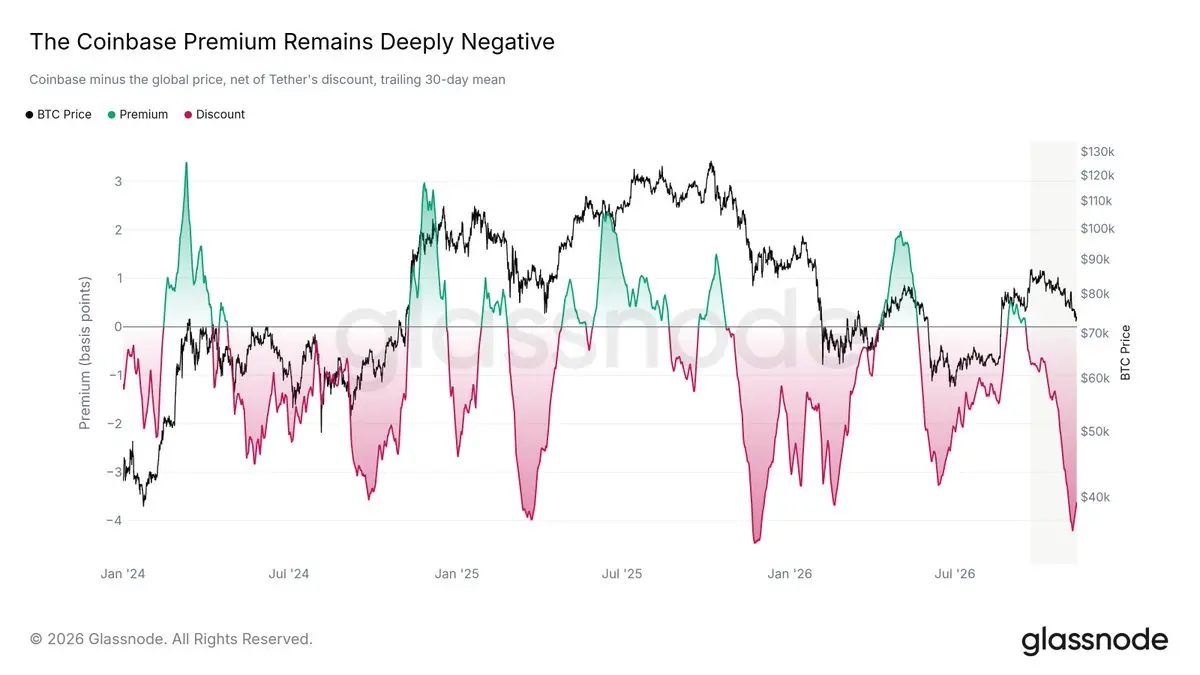
Glassnode’s 30-day average Coinbase premium—a comparison of Bitcoin’s Coinbase price with its global price—was negative throughout the decline from the September high and had reached its deepest discount since February. The report says its calculation removed the portion attributable to Tether trading below $1. It treated a premium that turned positive and stayed there for weeks as a possible sign of returning U.S. demand.
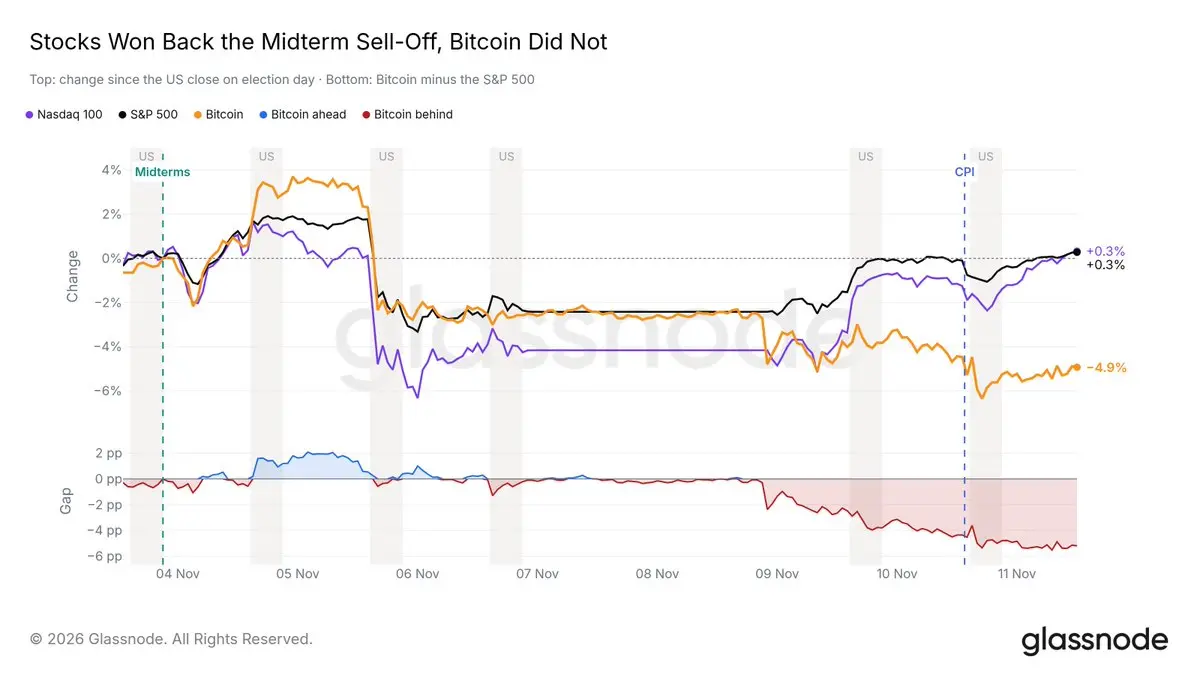
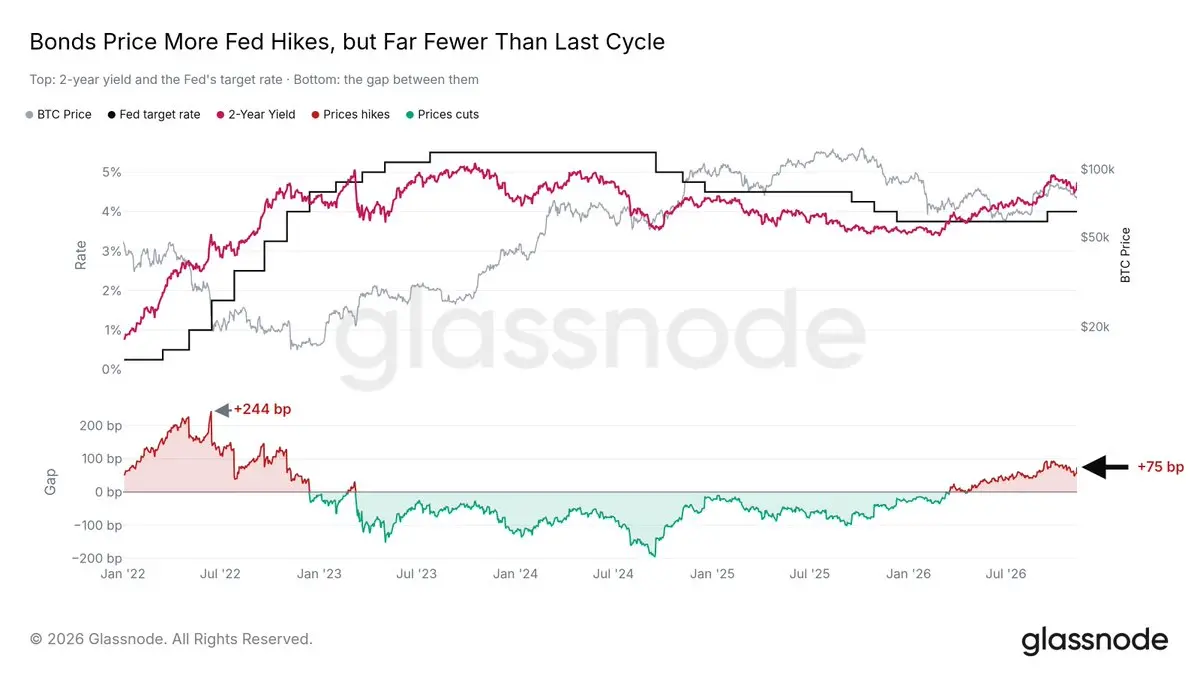
The report also placed Bitcoin’s performance in a cross-market context. It said a sell-off beginning November 5 affected both Bitcoin and equities, but their paths diverged from November 9: the S&P 500 and Nasdaq 100 recovered above their election-day closes, while Bitcoin fell again after the November 10 CPI release and remained about 5% below its election-day close of $77,800. Glassnode noted that the two-year U.S. Treasury yield was 4.75%, 75 basis points above the 4% Federal Reserve policy rate. It read that gap as pricing further tightening, while noting that it was narrower than the 244-basis-point peak recorded in June 2022 and had narrowed since late October.
Positioning offered a different signal
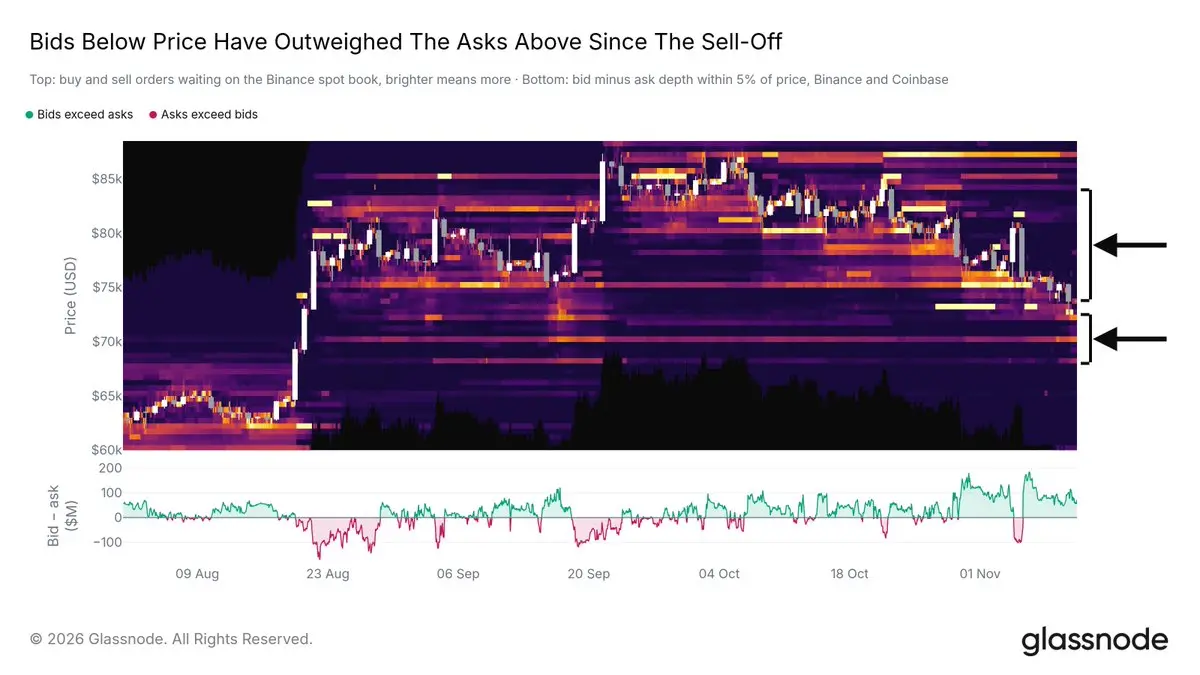
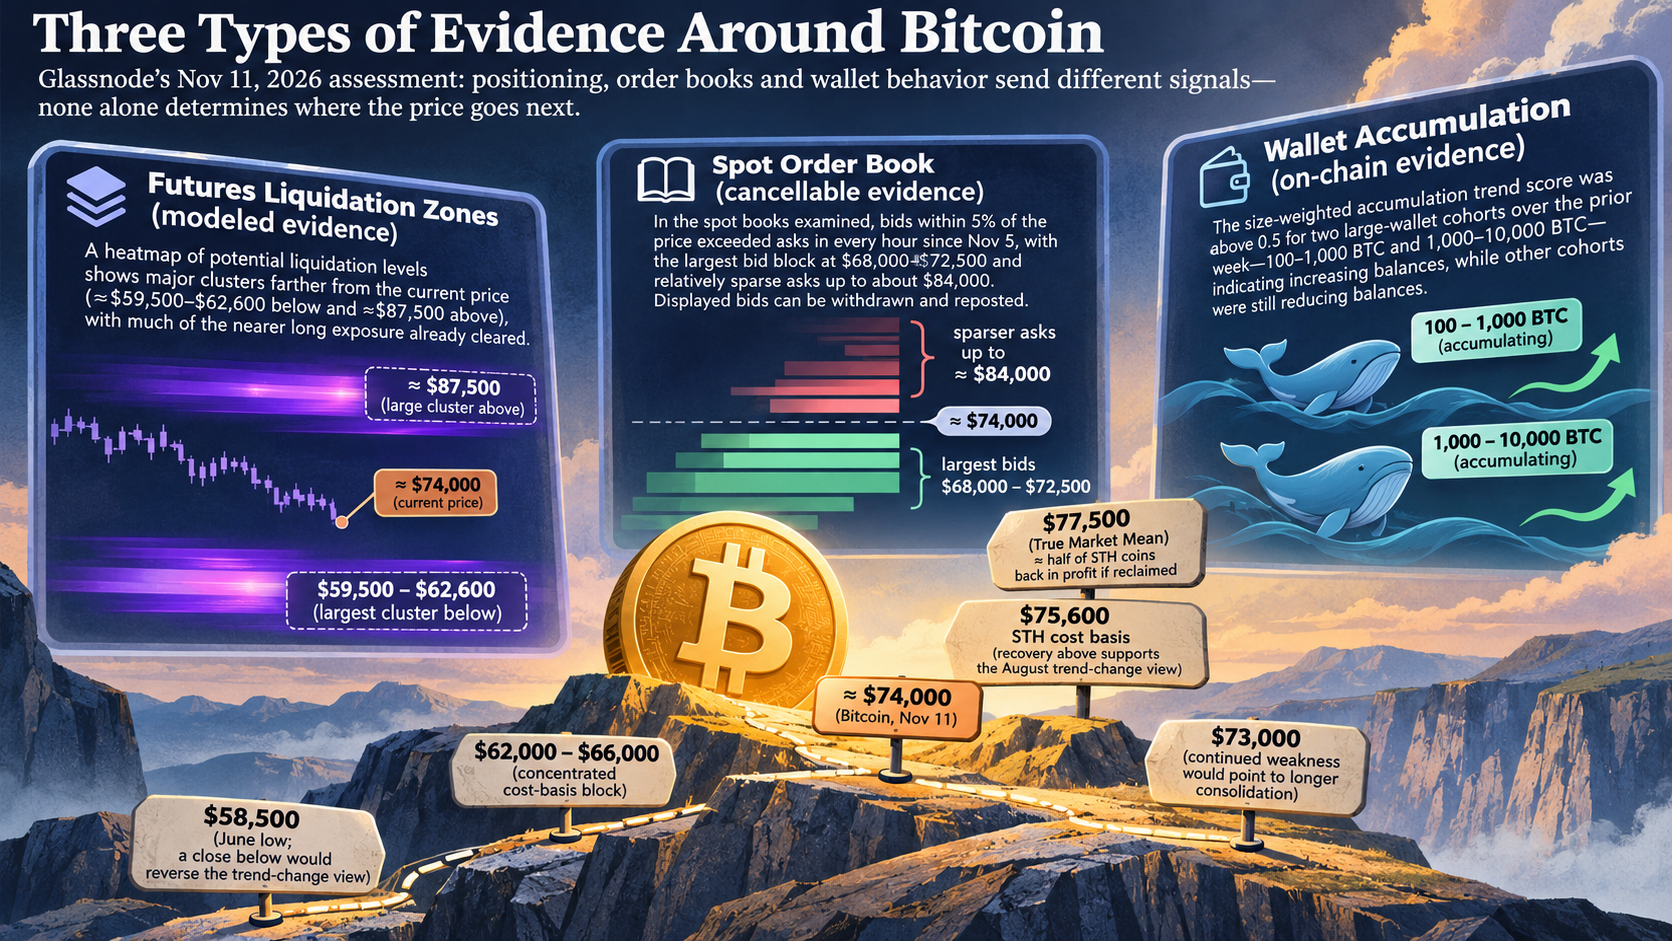
Glassnode’s liquidation heatmap indicated that the gradual decline since September had passed through much of the accumulated long-liquidation exposure near the price. Its largest cluster on the six-month view remained lower, at $59,500–$62,600; the largest cluster above was near $87,500. Open interest had returned to its level at the September high even though the price was about 15% lower. Glassnode interpreted that combination as traders adding shorts during the decline, which could require buying to close if the price rose. A heatmap models potential liquidation levels; it does not establish that they will be reached.
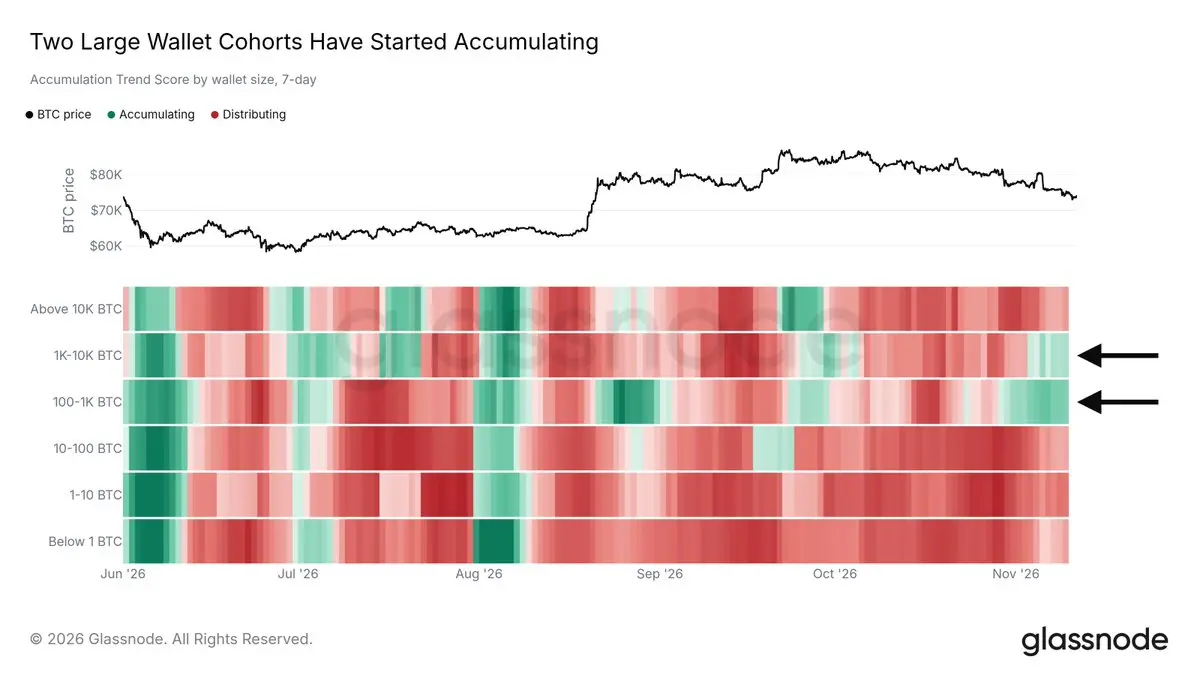
In the spot order books Glassnode examined, bids within 5% of the price exceeded asks in every hour since the November 5 sell-off. It located the largest bid block at $68,000–$72,500 and described relatively sparse asks above the immediate price area up to about $84,000. That apparent gap does not eliminate the potential selling pressure from short-term holders seeking to break even. Nor are displayed bids durable support: Glassnode noted that some were withdrawn during the sell-off and later reposted.
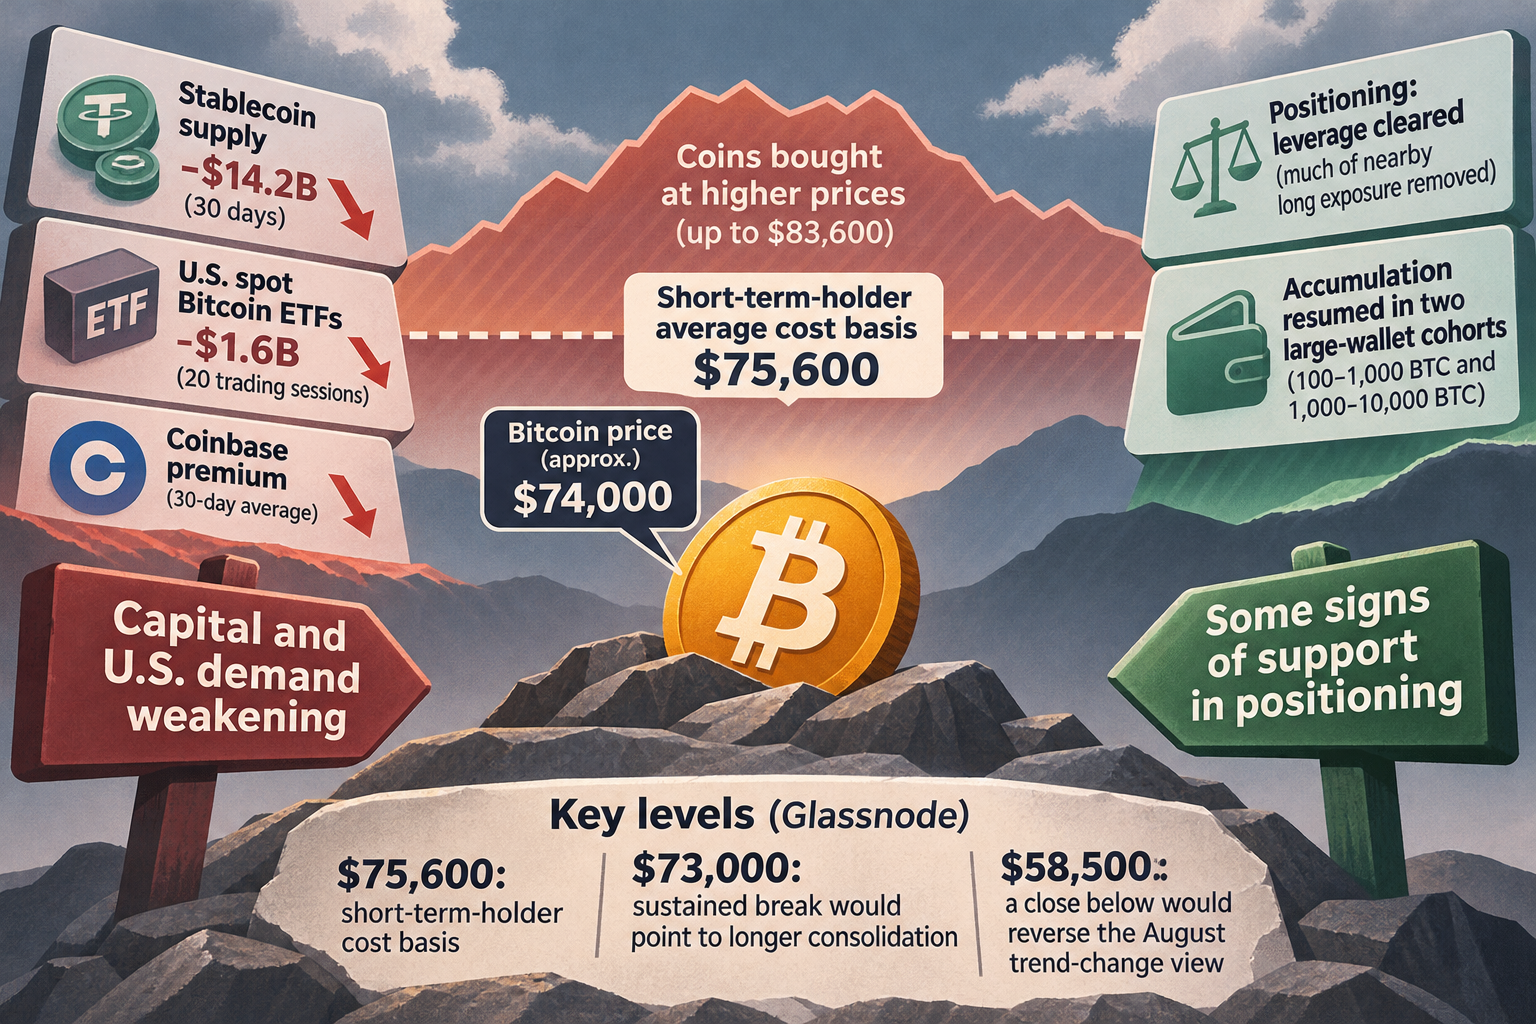
Glassnode’s size-weighted accumulation trend score showed two wallet cohorts above 0.5 over the preceding week: wallets holding 100–1,000 BTC and those holding 1,000–10,000 BTC. Scores closer to 1 indicate increasing balances; scores closer to 0 indicate decreasing balances. Both cohorts had largely been distributing in October, while every other cohort—from wallets below 1 BTC to those above 10,000 BTC—was still reducing balances. Glassnode cautioned that these two larger cohorts had also briefly shifted toward buying in late September without sustaining it.
What the report’s levels do—and do not—resolve
Glassnode identified a recovery above the $75,600 short-term-holder cost basis as support for an August trend-change interpretation. It said a sustained move below $73,000, the lower edge of the range it had flagged the previous week, would point to longer consolidation; a close below the $58,500 June low would reverse that interpretation. These were conditional readings of the report’s data, not confirmed outcomes.
Measurement times: Price and derivatives data were measured at 11:00 UTC on November 11, 2026, and order-book data at 09:00 UTC that day. ETF flows, stablecoin supply, cost-basis data and accumulation scores ran through November 9, 2026.
Source: chaincatcher.com (originally published 2026-11-11 23:17 UTC+8)