This is a restatement of a TechFlow article by Kuri (库里), published on 10 November 2026. The votes, parameters, and open items below were already on the record at that date. This is not a later update, and it is not evidence that the design has reached mainnet.
What the 9 November vote approved
On 9 November 2026, Aave DAO passed an ARFC for Babylon with a reported 100 percent yes vote. TechFlow attributes that result to a post Babylon published on X the same day. The ARFC accepts Babylon’s trustless Bitcoin vault (TBV) as the route for posting native bitcoin as collateral on Aave V4. A holder would lock BTC while keeping control of the keys and borrow assets such as USDT and USDC.
An ARFC is not execution. TechFlow reports that the proposal next enters an AIP, the on-chain vote that would implement it. The stated mainnet target is the end of 2026, with the number of participants and the size of the market limited at the start and widened in stages.
The proposal was first submitted in May and cleared a community temperature check in June. That check recorded 299,743 AAVE in favor and zero against. Aave founder Stani Kulechov posted support on the governance forum on 14 October 2026, the day the formal proposal was published. An earlier TechFlow tally cited in the article found that 73 of 74 binary Snapshot proposals at Aave that year had passed. The ARFC result sits inside that high approval rate. It does not show that the AIP will pass, or that mainnet terms will match the forum text.
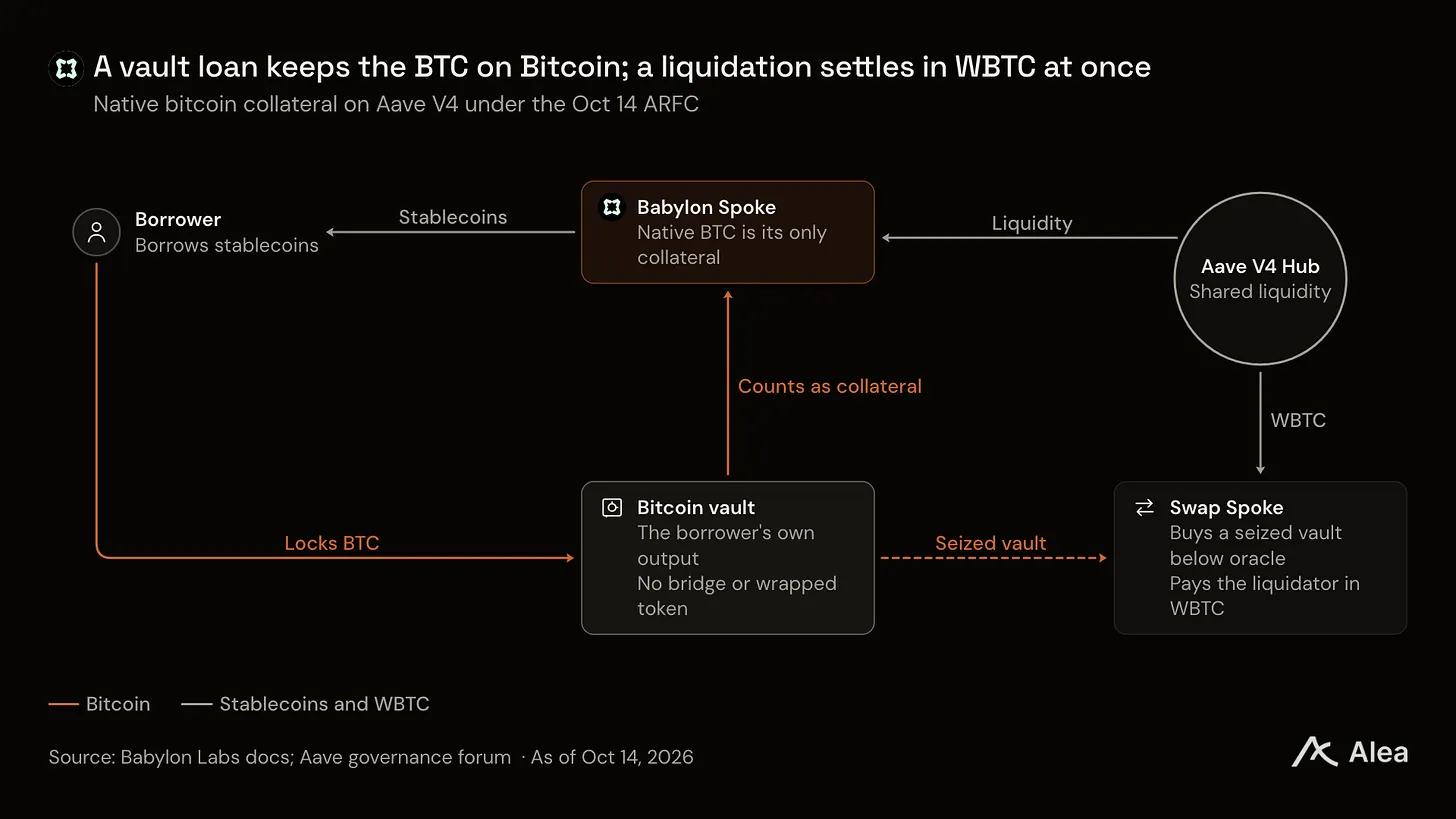
Mechanism: a receipt, not a custodian wrap
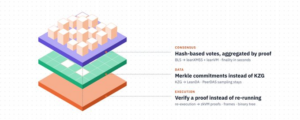
As published on the Aave governance forum and relayed by TechFlow, the borrower locks BTC in a Taproot vault on the Bitcoin chain. The coins stay at an address in the borrower’s name. Ethereum mints a non-transferable accounting token in the same amount as the locked bitcoin. That token is the collateral receipt inside Aave V4, against which the borrower can draw stablecoins.
LlamaRisk’s parameters in the proposal set the native-BTC collateral ratio at 78 percent and the maximum liquidation bonus at 5.55 percent. PANews, as cited by TechFlow, reported that this collateral ratio and the borrow rate are comparable to wrapped assets such as WBTC and cbBTC on the Aave V4 core market. Those figures are LlamaRisk parameters and a PANews comparison, not a new measurement.
TechFlow presents the design as filling a custody gap in bitcoin lending. Cointelegraph, cited in the piece, has described Aave’s existing bitcoin collateral as mainly wrapped assets such as WBTC and cbBTC, with a custodian holding the underlying BTC and the user bearing counterparty risk. TechFlow has also previously reported that Aave already runs a dedicated LBTC market. On TechFlow’s account, the Babylon proposal is the first Aave path aimed at unwrapped native bitcoin.
On price, Alea Research relayed Babylon’s estimate that annualized borrowing through the vault would be about 3 to 5 percent, against a 9 to 16 percent range Alea described as common on centralized lending platforms. That gap is a project estimate passed on by a research firm. The vault was not on Aave mainnet when the article was written, so it is not an observed rate. As of the end of the third quarter, about 40,481 BTC was staked on Babylon, all left on the Bitcoin chain in script form. The article does not treat that balance as the opening Aave collateral stock. Staking and a lending vault are related Babylon infrastructure, not the same position.
The fee waterfall
Only two items count toward the split, according to the proposal text: the liquidity fee Aave collects from interest paid by borrowers on this line, and fees from liquidation.
The schedule is tiered:
- The first $500,000 a year goes entirely to the Aave DAO.
- From $500,000 to $2 million, the Aave DAO receives 78 percent, Babylon 18 percent, and 4 percent is reserved for buybacks.
- Shares then rise by tier. On the portion above $6 million, the Aave DAO receives 61.5 percent, Babylon 31.5 percent, and the buyback share rises to 7 percent.
The source describes the bands between $2 million and $6 million only as stepwise increases. Percentages for those intermediate bands are not restated here because the article does not give them.
Buyback funds purchase tokens in the open market, 85 percent AAVE and 15 percent BABY. The purchased tokens are divided equally between the Aave DAO and the Babylon Foundation.
Alea Research ran one scenario: if this line produced $10 million of annual revenue, the Aave DAO would receive about $6.92 million, Babylon about $2.52 million, and buybacks about $560,000, of which about $84,000 would buy BABY. Alea called that the first channel through which borrower interest would feed value to BABY. It is an application of the fee schedule, not a claim that revenue will reach $10 million.
Against existing programs, the buyback is small. A proposal passed on the Aave governance forum in March cut AAVE’s own annual buyback budget from $50 million to $30 million. For BABY, Alea counted about 1.58 million newly issued tokens a day; at third-quarter prices, that issuance was worth about $7 million a year. Even the BABY slice of the $10 million scenario is a thin fraction of that issuance value. Whether it matters depends on revenue that did not yet exist and on a token-economics change that, as of 10 November 2026, had not been adopted.
Opening size, liquidation, and the pause key
The proposal’s initial credit line from Aave’s core pools is $8 million each of USDT and USDC, $2 million each of USDG and RLUSD, and $1 million of GHO, about $21 million in total. The native-BTC collateral cap is 300 BTC. Later increases require a new Aave DAO approval each time. Alea’s figure for effective loans across Aave V4 in September was about $310 million, so a fully drawn opening line would still be a small share of V4. The 300 BTC cap also limits how much of Babylon’s existing staked bitcoin could enter this market at the start.
Liquidation is the remaining dependence on wrapped bitcoin. Because the BTC stays on Bitcoin, the proposal specifies a settlement module: a liquidator buys the seized vault with WBTC, and an arbitrageur redeems BTC on the Bitcoin chain. Collateral posting is designed to drop the custodian. Settlement is not. If WBTC liquidity or the WBTC price relation is stressed, the exit from this native market still runs through a custodial asset.
Emergency pause is held by a 3-of-5 multisig that includes Aave Labs, LlamaRisk, and Babylon, among others. Pause and resume have no timelock. While the market is paused, repayment and liquidation are blocked as well. The multisig cannot transfer users’ bitcoin. Control is narrow on moving assets and wide on halting the market, including the actions a borrower would use to reduce exposure during a pause.
Still unresolved as of 10 November 2026
Two dates were still ahead, per Alea Research as cited by TechFlow. Babylon planned to submit a BABY token-economics adjustment to governance before the end of November 2026, with the aim of directing more new issuance toward the vault business. Separately, about 2,999 BTC staked through Gate custody was due to expire around 30 November 2026. If it was not renewed, Babylon’s staked balance would change. The source does not report either outcome.
TechFlow’s own closing point should stay conditional. Before mainnet, whether the BABY economics change is adopted will determine how much real buyback this lending line can direct to the two tokens. Other limits follow from the same text: the AIP had not been held; the end-of-2026 mainnet date was a target under a staged cap; the 3 to 5 percent borrowing cost was Babylon’s estimate; the $10 million split was a scenario; and liquidation still assumes a usable WBTC market. None of this is a view on whether AAVE or BABY is an attractive holding.
Source: techflowpost.com (originally published 2026-11-10 20:53 UTC+8)