As reported on November 19, 2026, Arbitrum-based derivatives protocol Variational had announced a $110 million Series B round on November 18, valuing it at $1.5 billion after the investment. Bain Capital Crypto led the round, with Dragonfly, HSG and Peak XV participating.
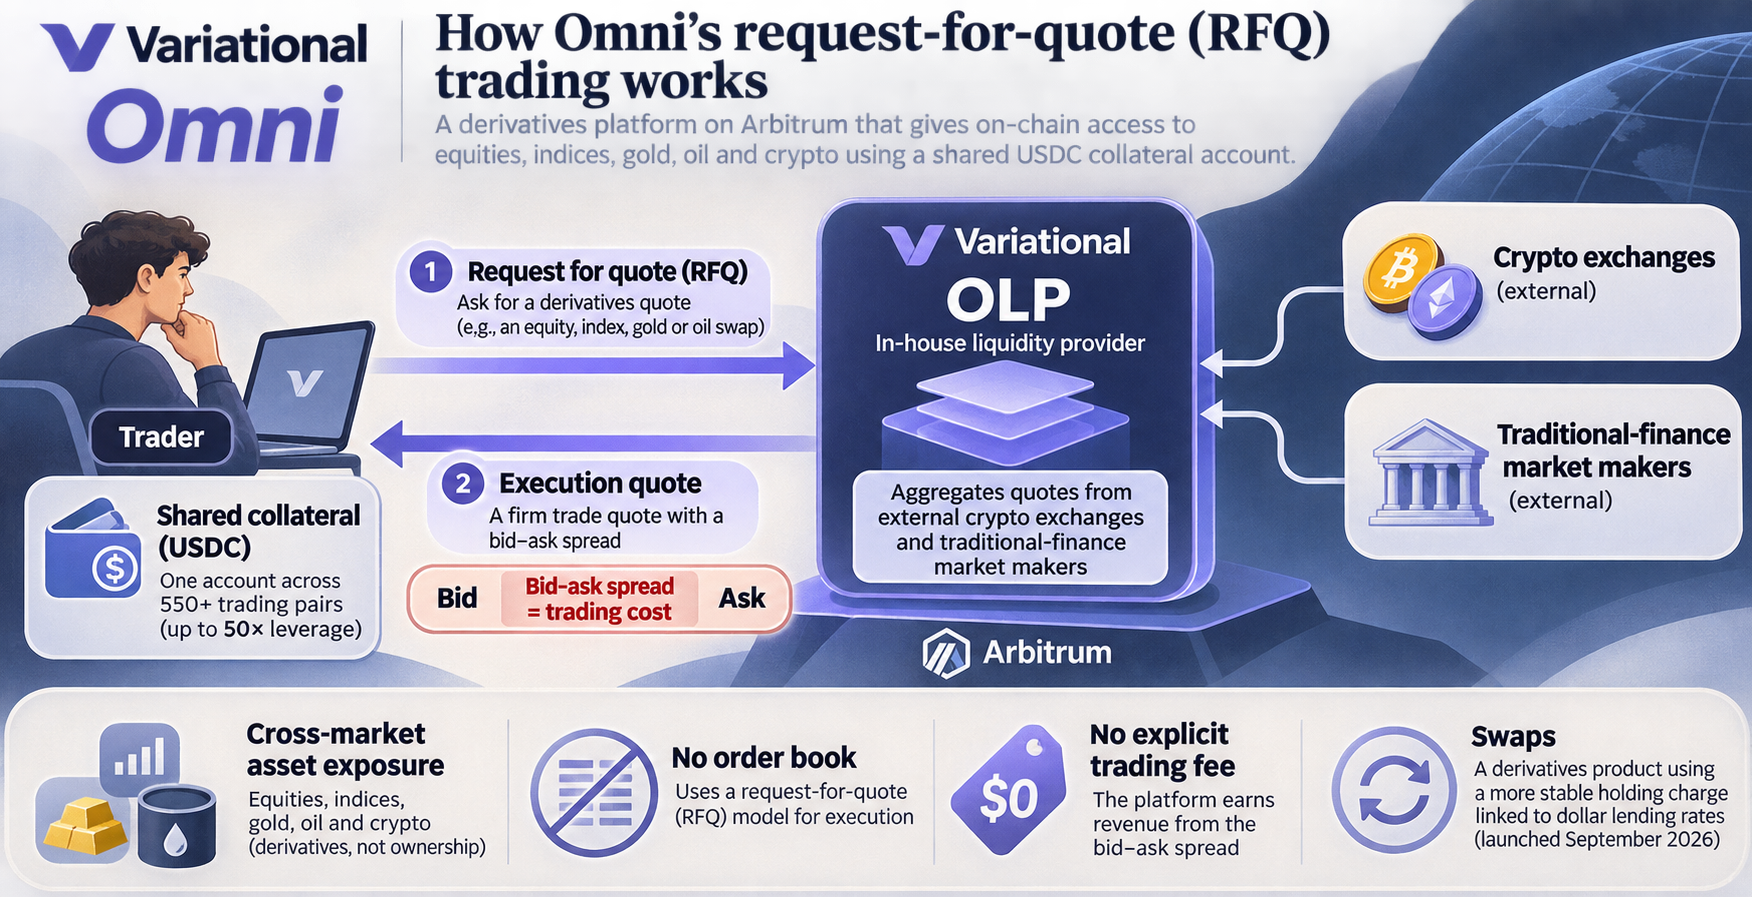
The research question is whether Variational’s trading model can support traditional-asset derivatives at scale. Its platform, Omni, uses a shared USDC collateral account for more than 550 cross-market trading pairs, with leverage of up to 50×. Those contracts provide exposure to assets such as equities, indices, gold and oil; they are not described as ownership of the underlying assets.
What the reported activity shows
Variational says Omni has processed more than $475 billion in cumulative volume and has more than 100,000 trading accounts since its 2025 launch. CEO Lucas Schuermann says equities, indices and traditional assets including gold and oil now account for more than half of Omni’s daily trading volume. These are platform-reported figures, not an independently identified dataset or a time series that establishes how the asset mix changed.
Rather than rely on an order book for each market, Variational uses a request-for-quote model. Its in-house liquidity provider, OLP, aggregates quotes from external crypto exchanges and traditional-finance market makers and presents users with an execution quote. The platform charges no explicit trading fee but earns revenue from the bid–ask spread. That distinction matters: a zero-fee quote is not necessarily a zero-cost trade.
Variational also introduced a product called Swaps in September 2026. It says cumulative Swaps volume has exceeded $80 billion. Instead of the periodically changing funding rates common to crypto perpetual contracts, the product uses a more stable holding charge linked to dollar lending rates, according to the report. The supplied material does not establish how that charge compares with alternatives across market conditions.
Capacity remains the test
Variational says demand for equity and commodity swaps repeatedly ran up against an initial $10 million open-interest limit per market. It intends to use the new funding to increase liquidity-pool capital and raise those limits. It also aims to make traditional-asset swaps available for trading around the clock before the end of 2026. That is a stated goal, not a capability the November report confirms as complete.
The reported volume and financing indicate substantial interest in the model. They do not, on their own, demonstrate that external quotes, shared collateral and risk limits will sustain deep traditional-asset markets when the underlying exchanges are closed.