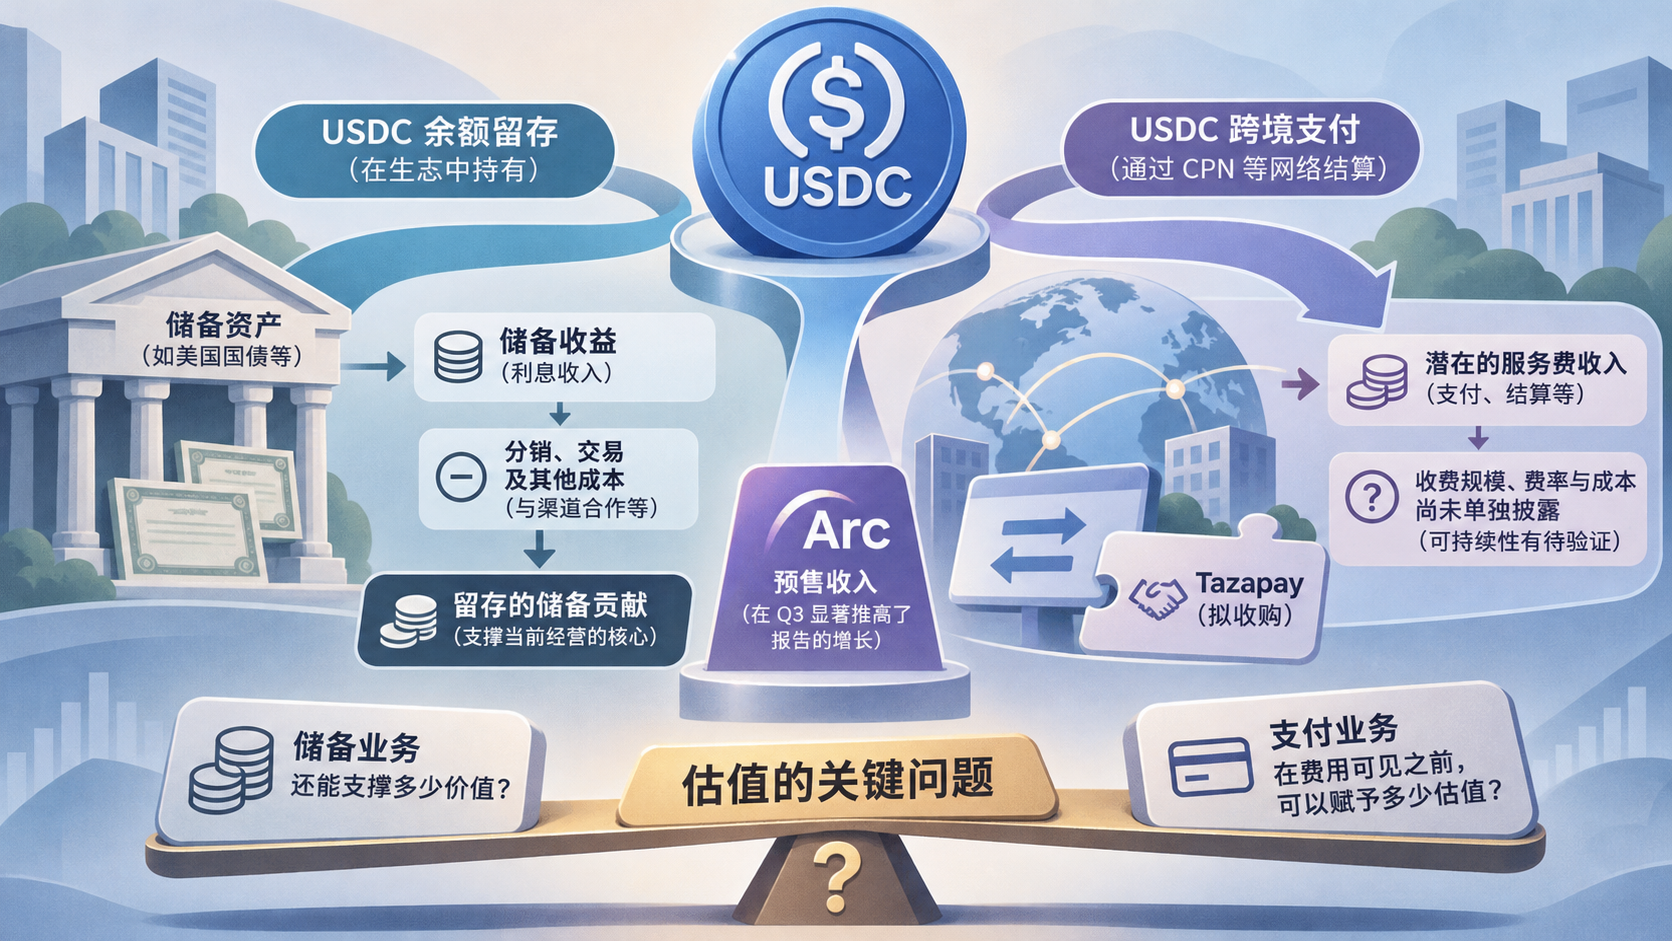
Circle’s third-quarter 2026 results pose a valuation question: how much of the business is supported by recurring reserve economics, and how much value can be assigned to payments before their fees are visible? In an analysis published on November 17, 2026, Web3小律 (Will 阿望) and 度刻 Fintech argued that Arc token presales materially affected the quarter’s reported growth. Their payment and share-price estimates are scenarios, not observed revenue or an independently established valuation.
What changed in Q3 earnings?
Circle reported $865 million in total revenue and reserve income, up about 23% from $701 million in Q2. Reserve income fell from $668 million to $658 million, while other revenue rose from $34 million to $207 million. Approximately $182 million of Q3 other revenue came from Arc token presales. According to the analysis, Circle recognized roughly three-quarters of the presale revenue after the public mainnet launch and token minting and delivery.
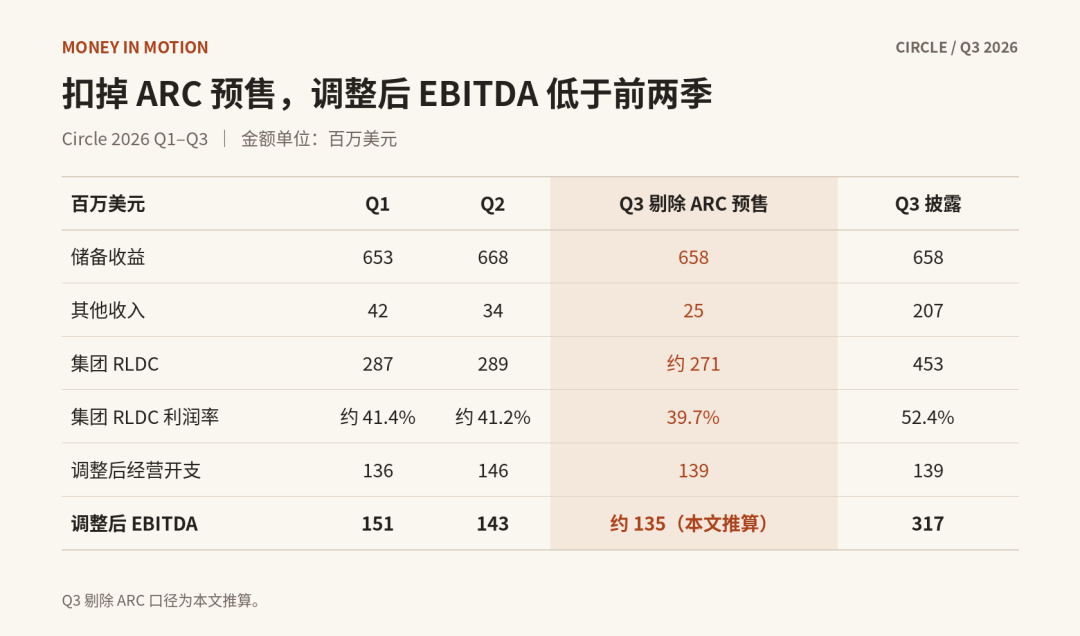
Removing the Arc presale amount leaves approximately $683 million in Q3 total revenue and reserve income, and about $25 million in other revenue. The latter compares with $34 million in Q2 and $42 million in Q1. Management attributed part of the decline to fewer blockchain-integration projects reaching revenue recognition during Q3.
Reported adjusted EBITDA was $317 million, versus $143 million in Q2. The authors’ rough comparison subtracts the $182 million Arc presale revenue directly from adjusted EBITDA, producing approximately $135 million—below Q2’s $143 million and Q1’s $151 million. That subtraction is not a separately reported adjusted EBITDA measure and does not establish Arc’s net profit contribution.
Reserve income: balance and distribution costs
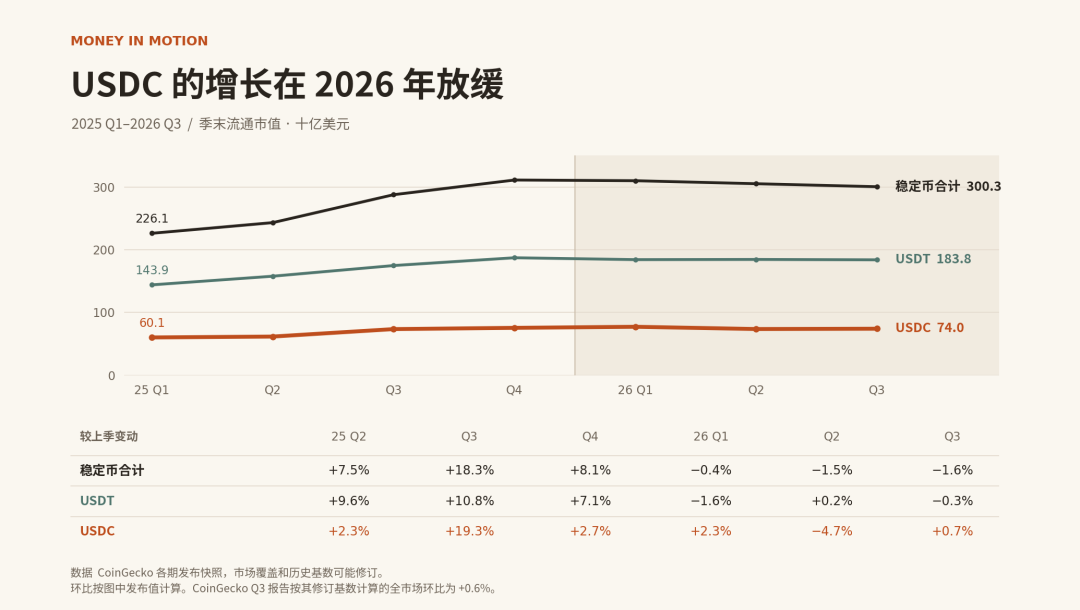
Circle’s Q3 average USDC circulation was $73.3 billion, down 4% quarter over quarter. A reserve yield of 3.54% was not enough to prevent reserve income from declining. The authors stress that quarterly average circulation, rather than quarter-end supply, is the relevant balance for interpreting that income.
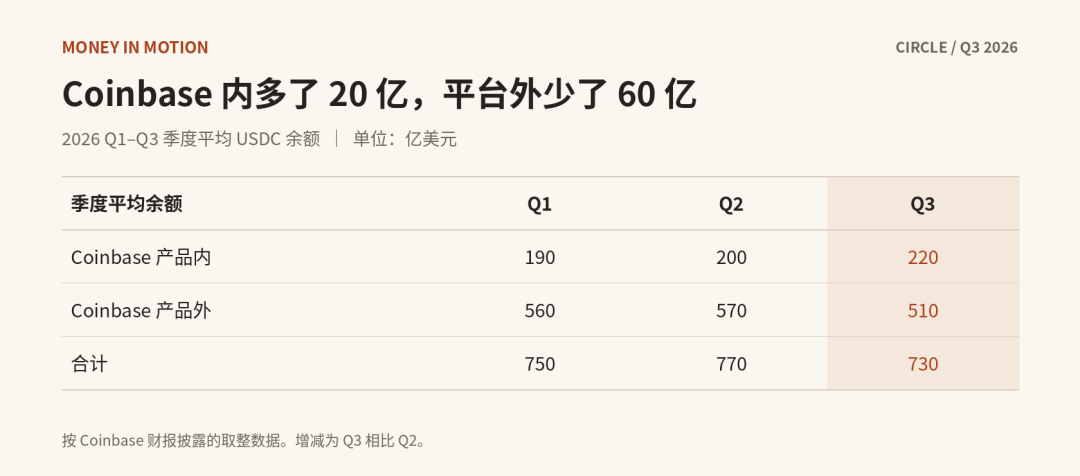
After associated distribution and transaction costs, Circle retained $37.80 per $100 of reserve income, down from $38.60 in Q2. The analysis reports that Circle’s CFO attributed most of this change to the Hyperliquid arrangement running for a full quarter, with related USDC balances held at Coinbase. Citing Coinbase’s rounded disclosures, the authors say average USDC balances across the network fell by $4 billion: balances within Coinbase products rose by $2 billion, while those outside its platform fell by $6 billion. They also note that Circle and Coinbase renewed their original terms; Binance’s renewed revenue-sharing terms were not yet reflected for a full quarter and would be in Q4.
Circle’s group RLDC margin—revenue and reserve income less distribution, transaction and other costs, divided by total revenue and reserve income—rose from 41.2% to 52.4%. That group measure includes the quarter’s Arc presale revenue; it should not be confused with the narrower reserve-income retention figure.
Can payment volume become recurring fees?
Circle Payments Network (CPN) connects financial institutions for stablecoin-based cross-border settlement. Its quarter-end annualized payment volume rose from $8.3 billion in Q1 to $14.7 billion in Q2 and $41.3 billion in Q3. The Q3 figure annualizes approximately $3.4 billion of volume over the final 30 days; it is not a full year of realized payments.
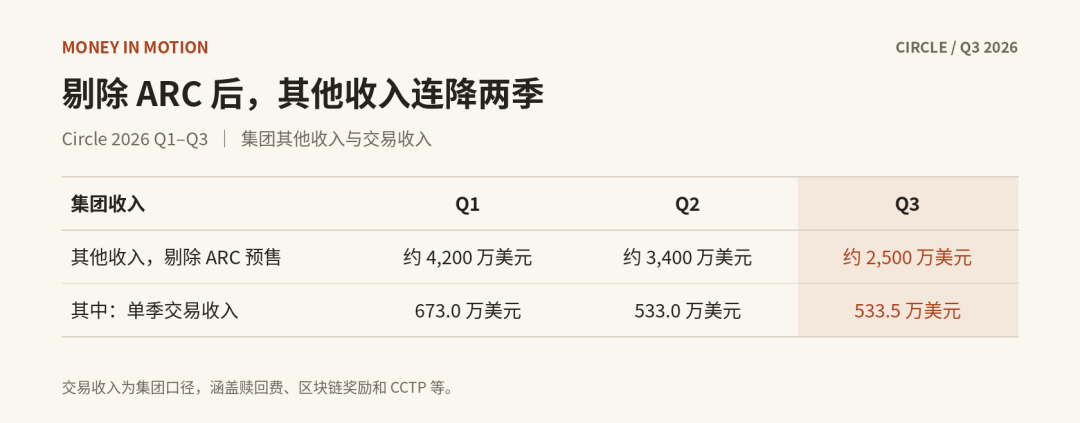
At an assumed fee of 5 basis points, sustaining the Q3 exit rate for a year would imply about $20.65 million in annual revenue. Circle does not separately disclose CPN fees in the group transaction-revenue line, which also includes redemption fees, blockchain rewards and digital-asset transaction infrastructure, including CCTP. The analysis therefore cannot determine how much of CPN’s volume was charged or how much Circle collected.
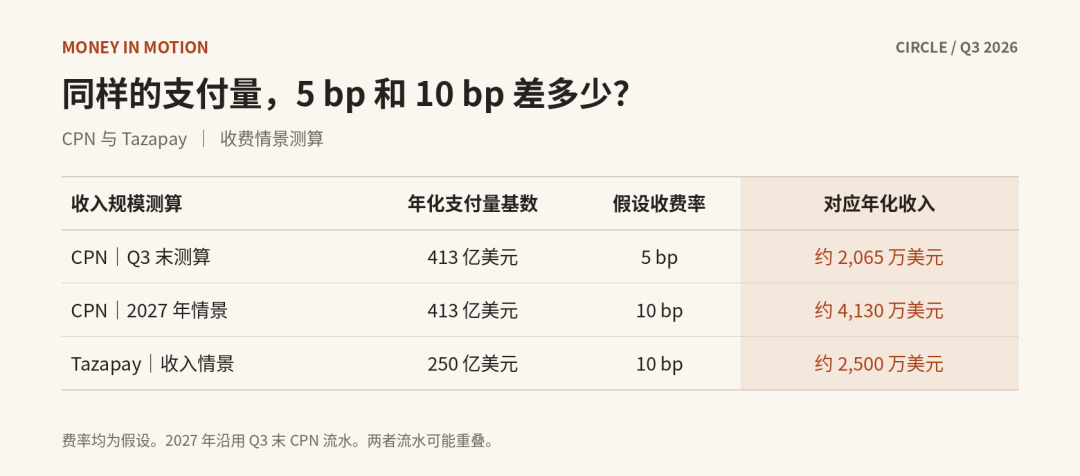
Circle also proposed acquiring the Tazapay shares it did not already own for approximately $400 million in stock, subject to closing adjustments. Tazapay, already a CPN design partner, reported annualized payment volume above $25 billion, about 60% of it involving stablecoins. The authors see its customer relationships and local payout network as potential ways for Circle to capture more payment activity. That is a prospective benefit, not recognized income.
Applying an assumed 10-basis-point fee to CPN’s $41.3 billion Q3 exit rate yields $41.3 million in annualized revenue. This uses the same CPN volume as the 5-basis-point example; the two estimates cannot be added together, and Tazapay’s volume may overlap substantially. At a hypothetical eight-times earnings purchase multiple, a $400 million acquisition price would require about $50 million in annual after-tax profit to support that assumption. The source does not establish Tazapay’s actual profit or the transaction’s ultimate return.
What supports the valuation range?
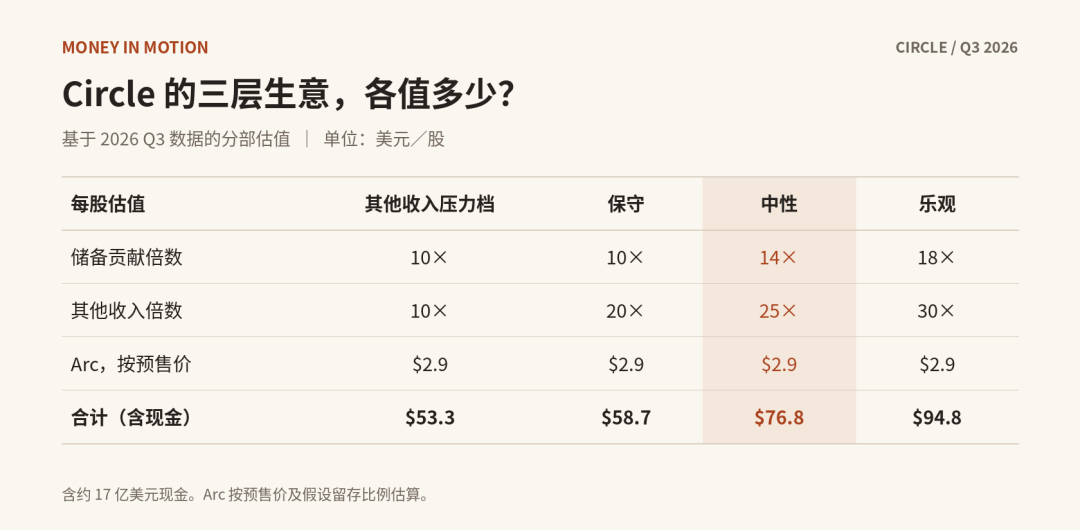
The authors’ three-part model assigns separate values to reserve operations, other revenue and Arc. It uses approximately $984 million of annualized Q3 reserve contribution, $138 million as the midpoint of adjusted full-year other-revenue guidance, roughly $1.7 billion in cash and 256 million shares. After removing recognized Arc presale revenue, the cited other-revenue guidance range is approximately $128 million–$148 million.
For reserves, the model applies 10, 14 or 18 times the contribution remaining after distribution, transaction and other costs—but before corporate operating expenses and taxes. For other revenue, it applies 20, 25 or 30 times revenue, with a 10-times stress case. It estimates Arc at $750 million, using a $0.30 presale price, an initial supply of 10 billion tokens and an assumed 25% post-sale holding. These are valuation inputs, not independently observed market values. Expected Tazapay earnings and newly issued acquisition shares are excluded because the deal was expected to close in 2027.
On those assumptions, the authors calculate an illustrative range of approximately $59–$95 per share, with a midpoint near $77. The range is especially sensitive to reserve balances, distribution economics and whether payment activity becomes sustained fee income. As further context, the analysis says Mizuho and Citi both attributed much of Q3’s earnings surprise to Arc presales. It describes Mizuho’s forecast of a Q4 net reserve margin in the low 30% range as a sell-side estimate, while Citi’s approximately $400 million forecast for 2027 other revenue does not, in the cited public summary, isolate recurring payment fees.
The evidence available as of the November 17, 2026 analysis supports a narrower conclusion than a payment-led valuation: CPN volume was growing, but Circle had not disclosed the fees and costs needed to measure its recurring contribution. The next test for the model was whether payment revenue could become visible while reserve balances and distribution terms continued to change.