As reported on November 19, 2026, depositors in Sky’s stUSDS lending pool faced a shortage of immediately withdrawable funds. The episode centers on a large USDS loan attributed by a community researcher to a wallet associated with Sky co-founder Rune Christensen. That attribution, and the distinction between an illiquid pool and an unpaid loan, matter to assessing the risk.
What the reported figures show
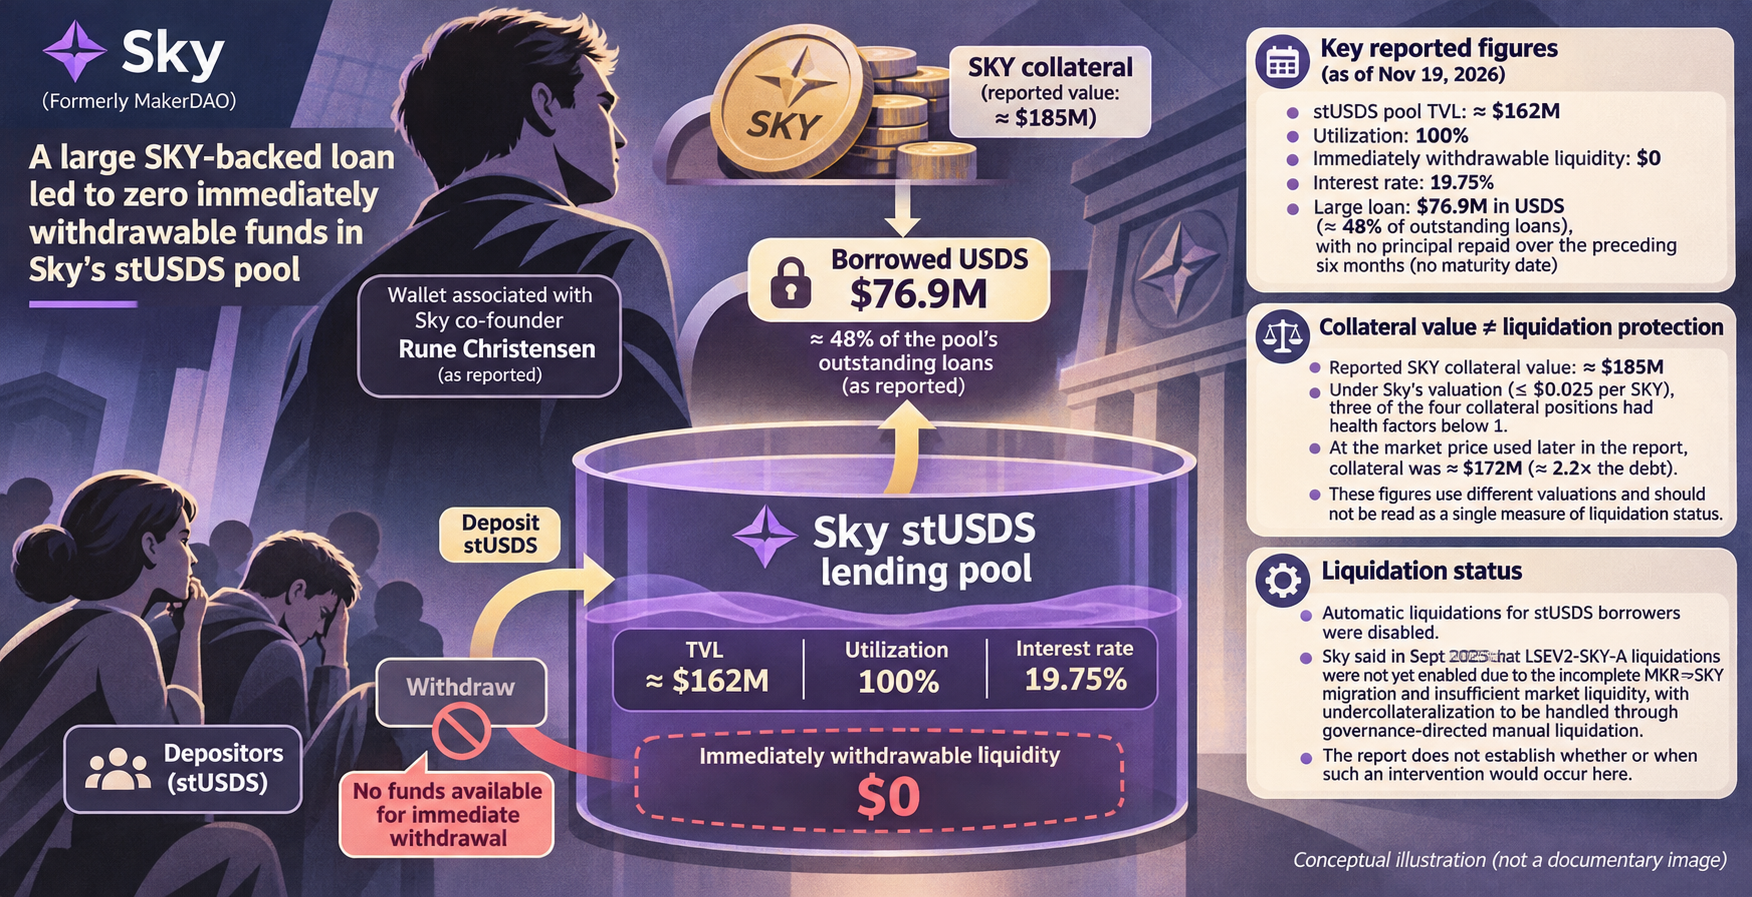
Community user @punkquidity said the associated wallet had borrowed $76.9 million in USDS against SKY collateral and had repaid no principal over the preceding six months. The debt represented nearly 48% of the pool’s outstanding loans, according to their account. The loan has no maturity date, so the absence of principal repayments does not itself breach the protocol’s rules.
@punkquidity also reported that the last freely withdrawable funds had left the pool on the evening of November 10. They described a similar period of near-zero available liquidity on October 31, which ended that evening.
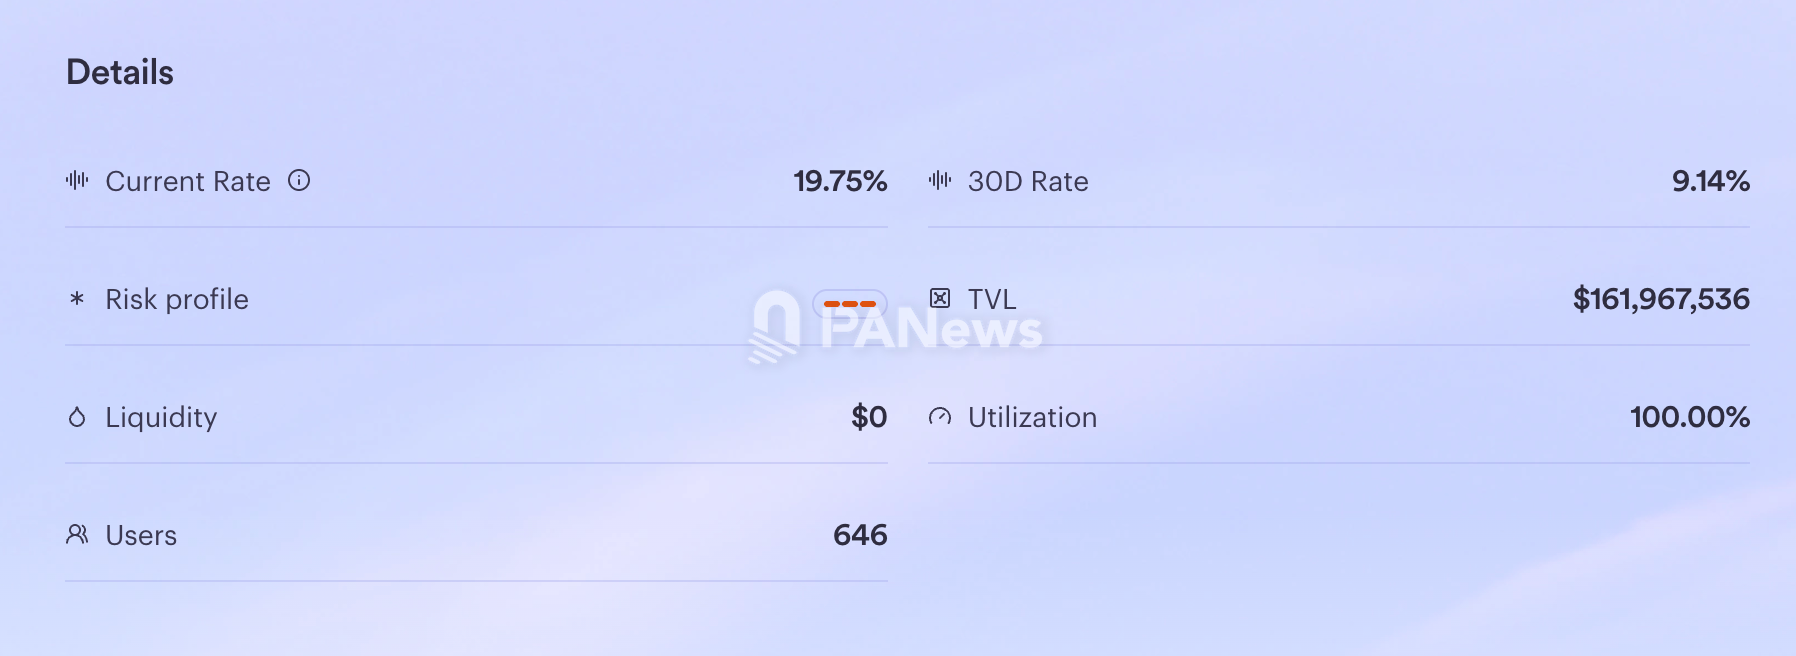
Sky’s website showed that, as of November 19, the stUSDS pool had approximately $162 million in total value locked, 100% utilization, no liquidity available for immediate withdrawal and a 19.75% interest rate. Depositors seeking to withdraw had to wait for loan repayments or fresh deposits. A higher rate may encourage either, but does not itself create funds available for withdrawal.
Collateral value is not the same as liquidation protection
The original report described the SKY posted as collateral as worth approximately $185 million when discussing the loan. It also cited DeBank data showing that, under Sky’s valuation of no more than $0.025 per SKY for this loan, three of the associated wallet’s four collateral positions had health factors below 1. At the market price used later in the report, the collateral was worth approximately $172 million, or about 2.2 times the debt. Those figures use different valuations; they should not be read as a single measure of the positions’ liquidation status.
Automatic liquidations for stUSDS borrowers were disabled, according to the report, so a position crossing its liquidation threshold would not be forcibly liquidated through that mechanism. Sky had said in September 2025, while preparing stUSDS, that liquidations for LSEV2-SKY-A were not yet enabled because much MKR had not migrated to SKY and market liquidity was insufficient. Its stated approach was to handle undercollateralization through governance-directed manual liquidation instead. The report does not establish whether or when such an intervention would occur here.
What the loan does not establish
Some observers questioned whether borrowing against SKY amounted to cashing out without selling the token. The mechanism does give a borrower USDS while retaining ownership of pledged SKY, but the report provides no evidence of how the borrowed funds were spent.
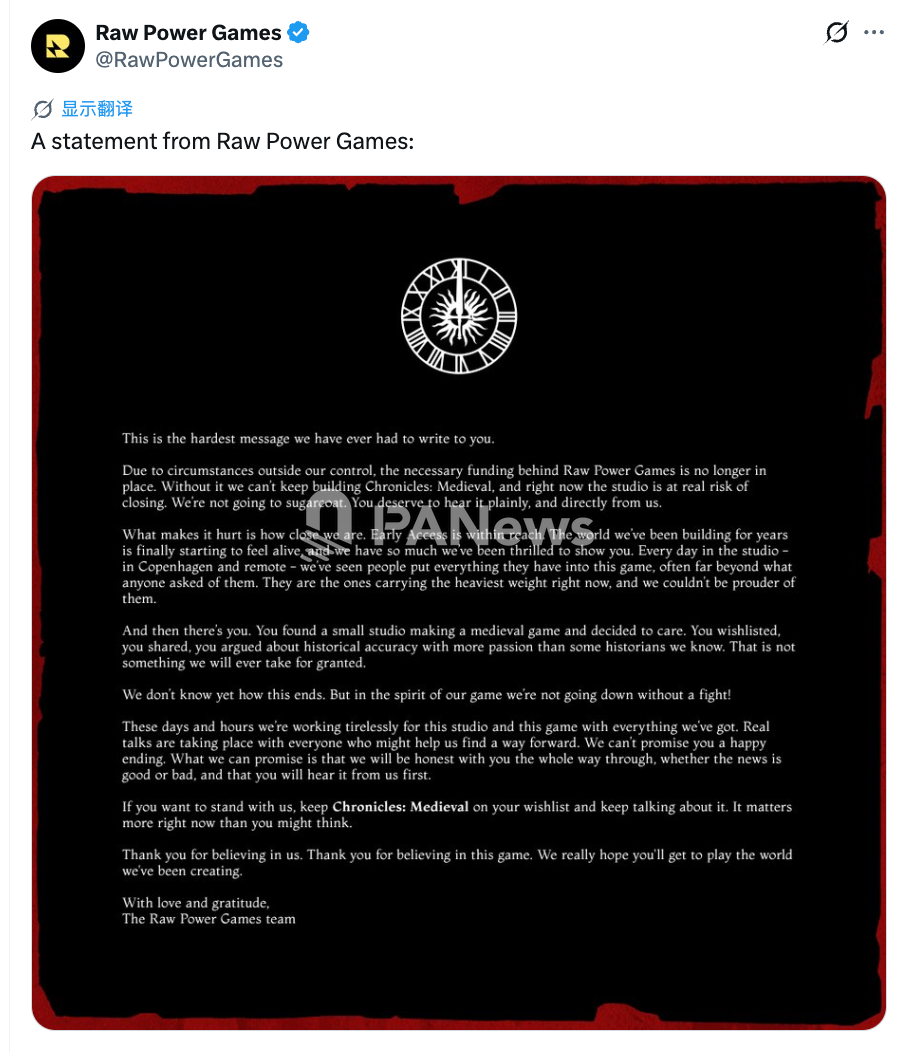
It also discusses financial trouble at Raw Power Games, a studio backed by Christensen. On October 30, the studio said an interruption in funding put it at risk of closure and could prevent completion of Chronicles: Medieval. Coffee Stain subsequently announced an acquisition of the studio’s intellectual property for approximately $5.42 million and took over development of related projects. No evidence presented in the report links the Sky loan proceeds to the studio.
The documented concern is narrower: a large, outstanding loan coincided with zero immediately available pool liquidity, while automatic liquidation was unavailable. The borrower’s eventual repayment, new deposits and any governance response remained unresolved in the November 19 report.