RootData Research’s report, published on November 13, 2026, examines crypto-platform stock derivatives and tokenized-stock spot products using data from August 1 through October 31, 2026. Its central finding is that derivatives trading remained concentrated among a few exchanges, while trading volume, open interest and order-book depth did not move in lockstep.
Derivatives: volume recovered, but not to August levels
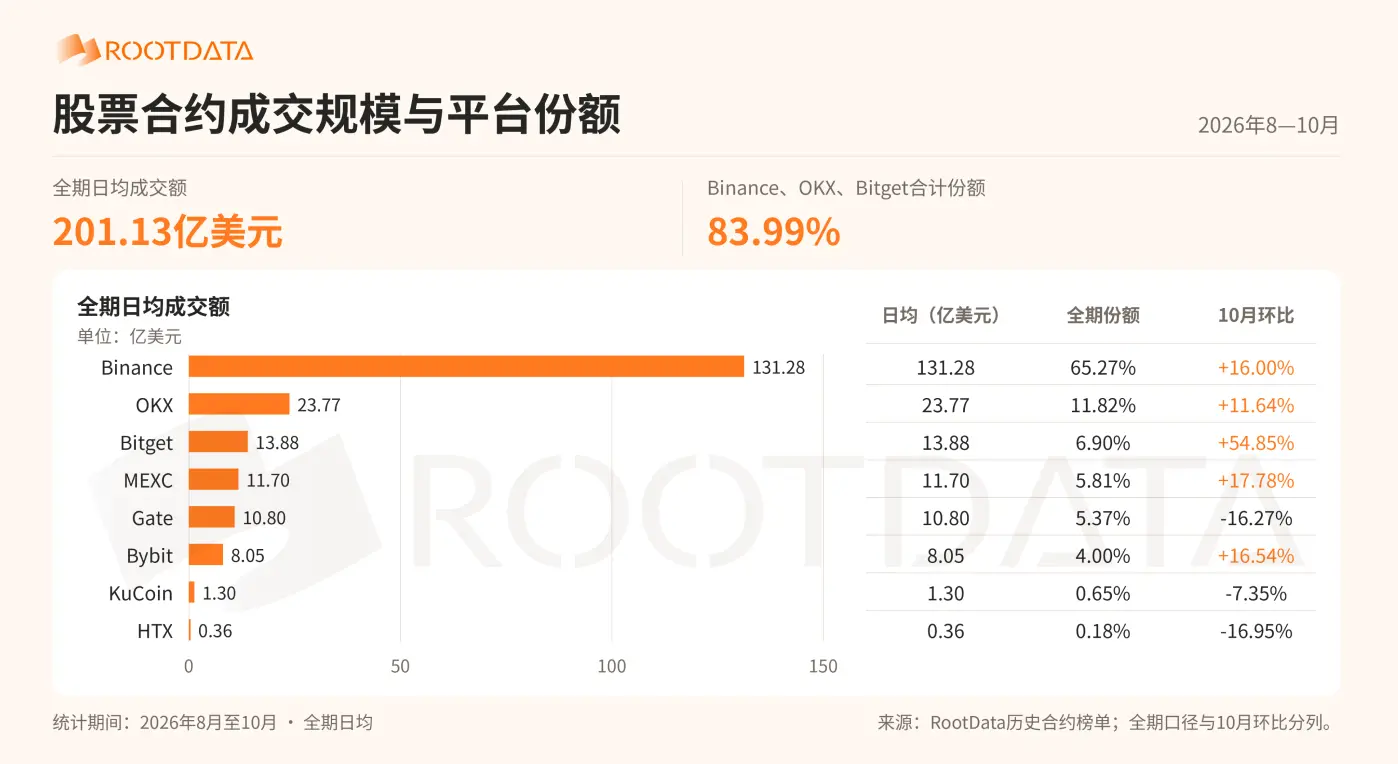
Across Binance, OKX, Bitget, Bybit, Gate, MEXC, KuCoin and HTX, RootData reports approximately $1.79 trillion in stock-derivatives volume over the period, or $20.113 billion per day on average. The sample covers stock and ETF perpetual contracts quoted or settled in stablecoins such as USDT and USDC.
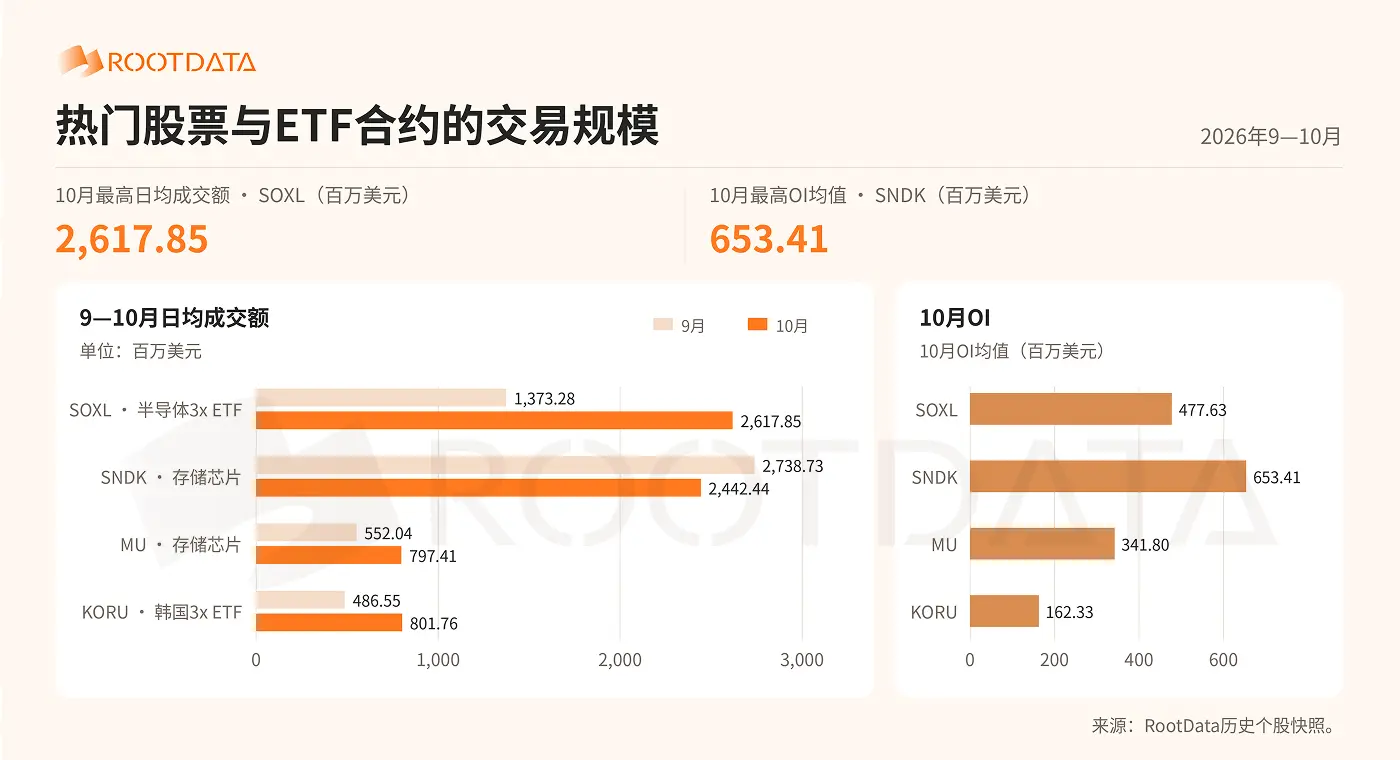
Average daily volume fell from $23.360 billion in August to $17.041 billion in September, then recovered to $19.809 billion in October. Binance, OKX and Bitget accounted for a combined 83.99% of the period’s reported volume; the top three platforms’ combined monthly share rose from 81.59% to 87.22%.
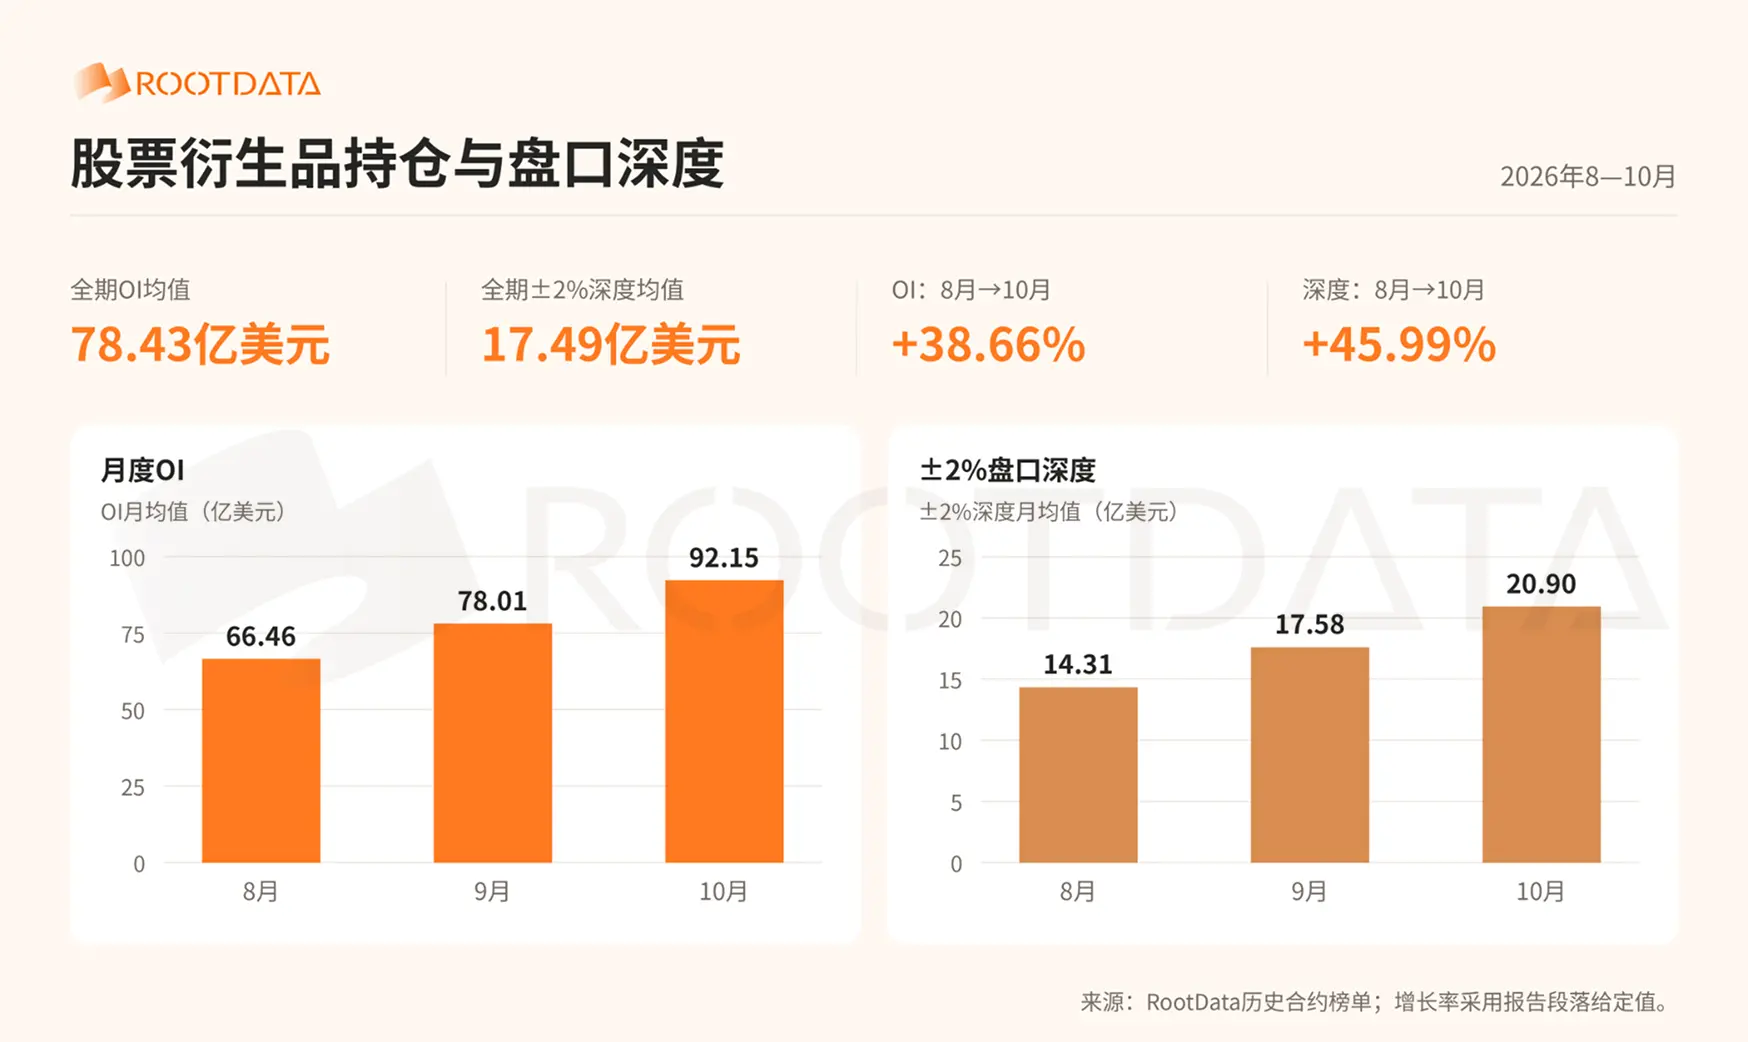
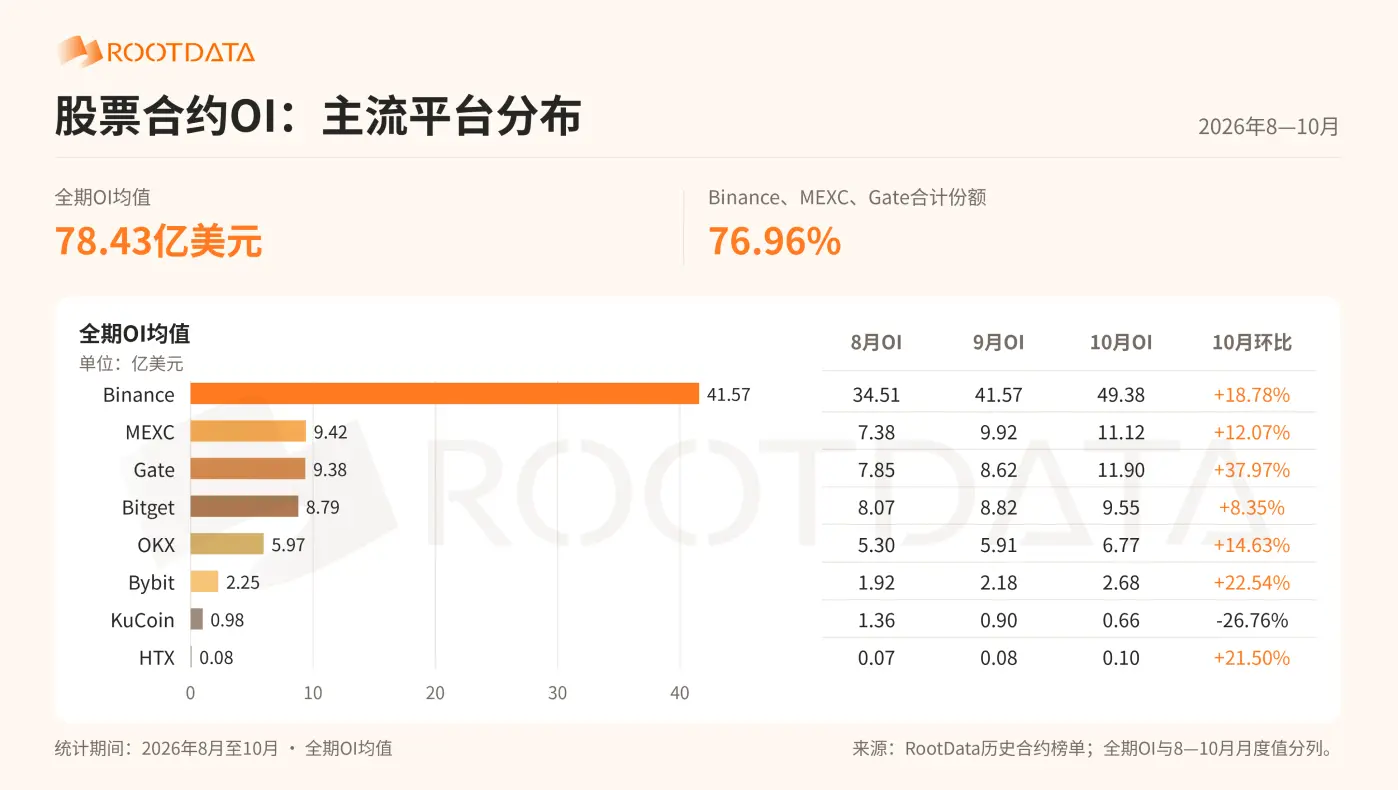
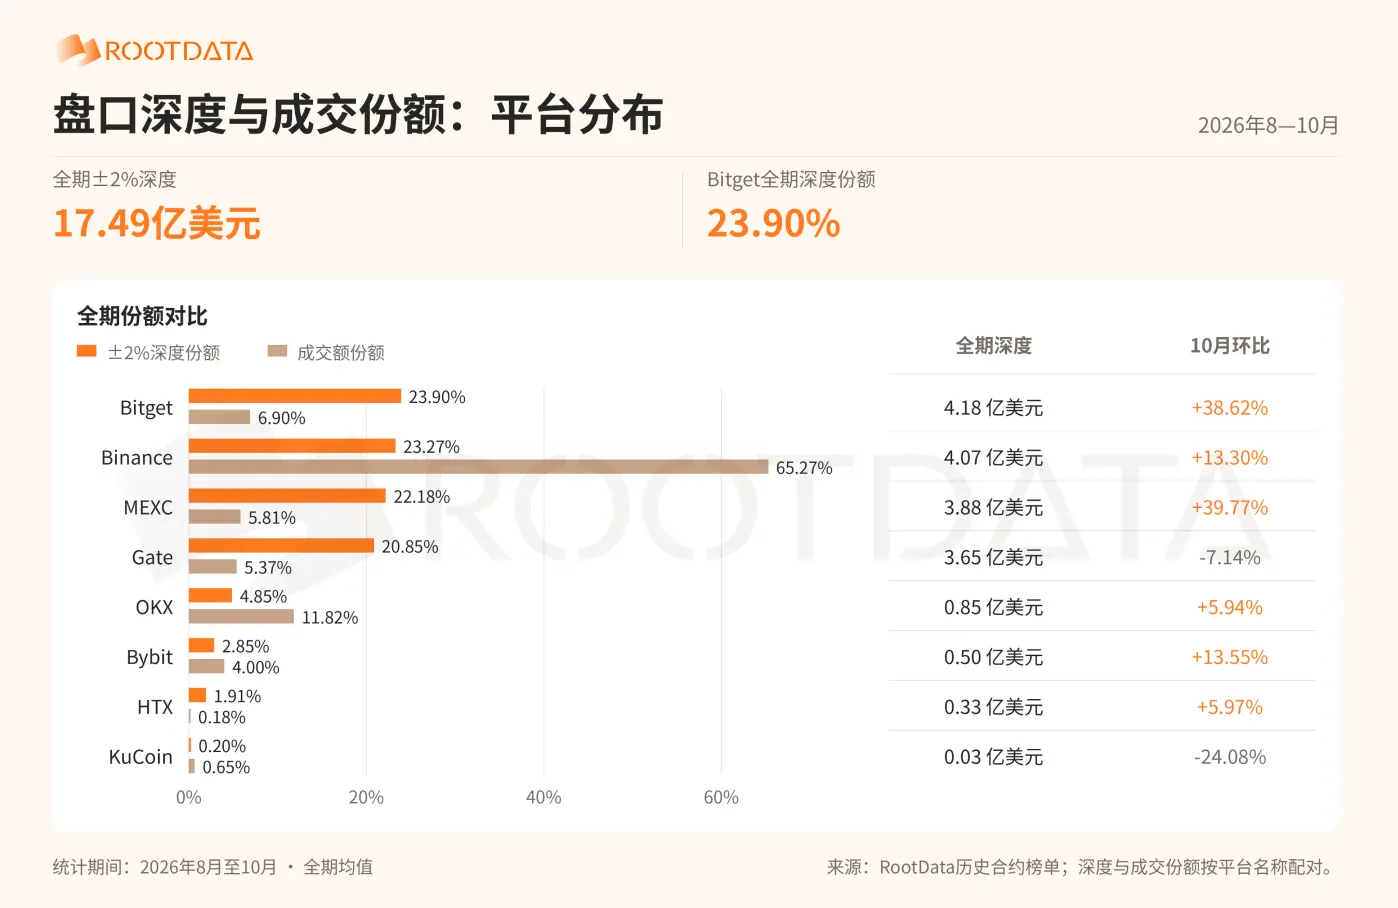
Open interest and visible liquidity followed a different path. RootData puts average daily open interest across the eight exchanges at $7.843 billion and average daily depth within ±2% of the quoted price at $1.749 billion. Both measures increased through the period: October averages reached $9.215 billion and $2.090 billion, respectively. The report interprets September’s rising open interest and depth alongside falling volume as a shift toward holding positions and continued order placement. Those aggregate measures, however, do not establish how reliably quotes would hold during a volatile event.
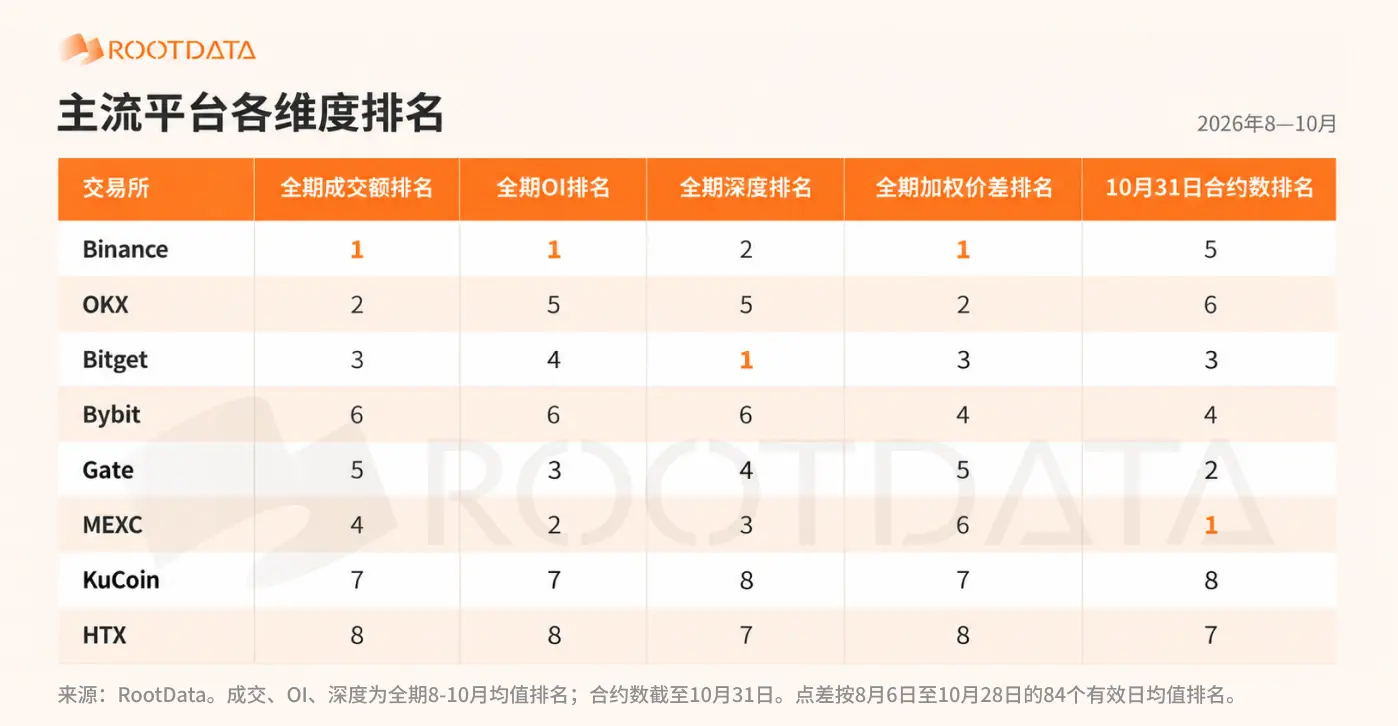
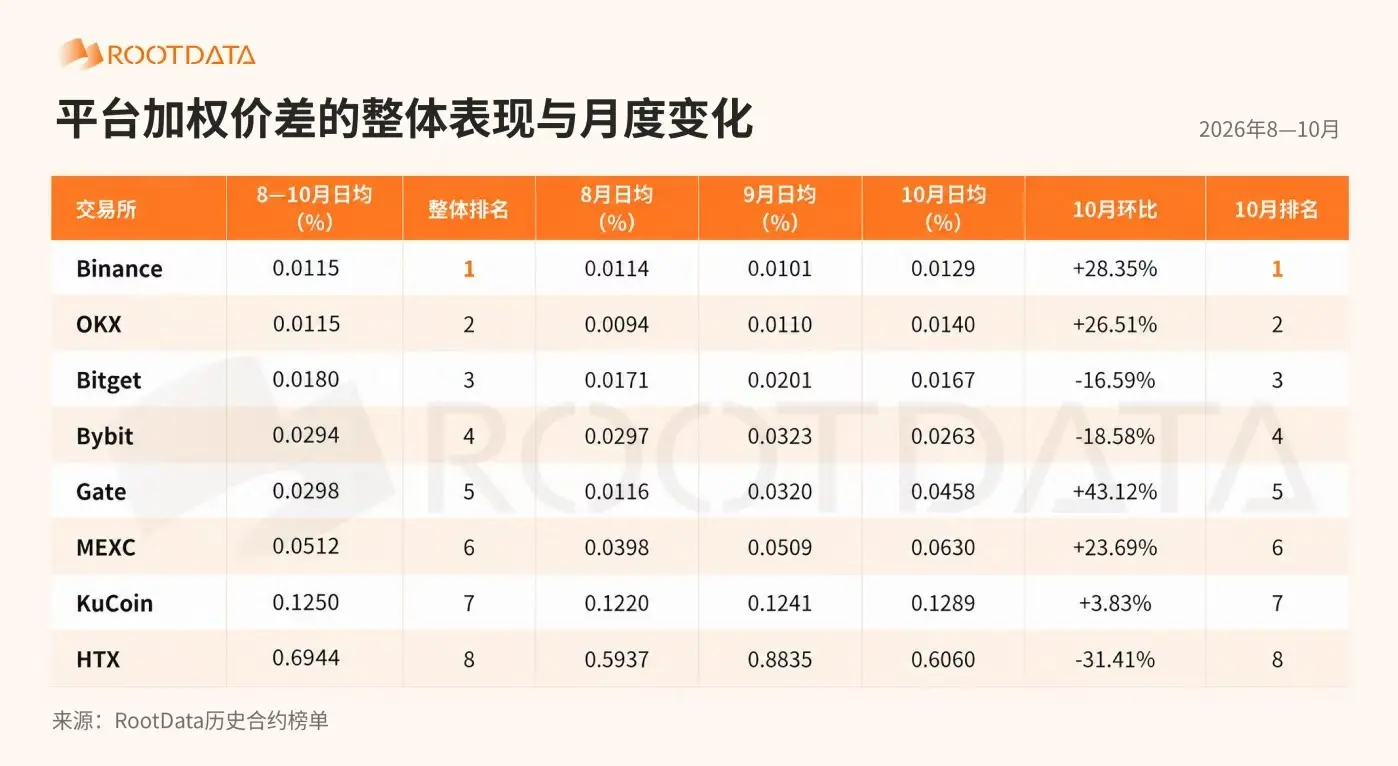
The rankings also depend on the metric. Binance led in average daily volume and open interest, while Bitget had the highest average ±2% depth, at $418 million, compared with Binance’s $407 million. Binance and OKX each recorded a reported daily weighted spread of 0.0115%; Bitget’s was 0.018%. These are period averages, not guarantees of execution quality for a particular contract or trade size.
Tokenized stocks: a smaller market with different product designs
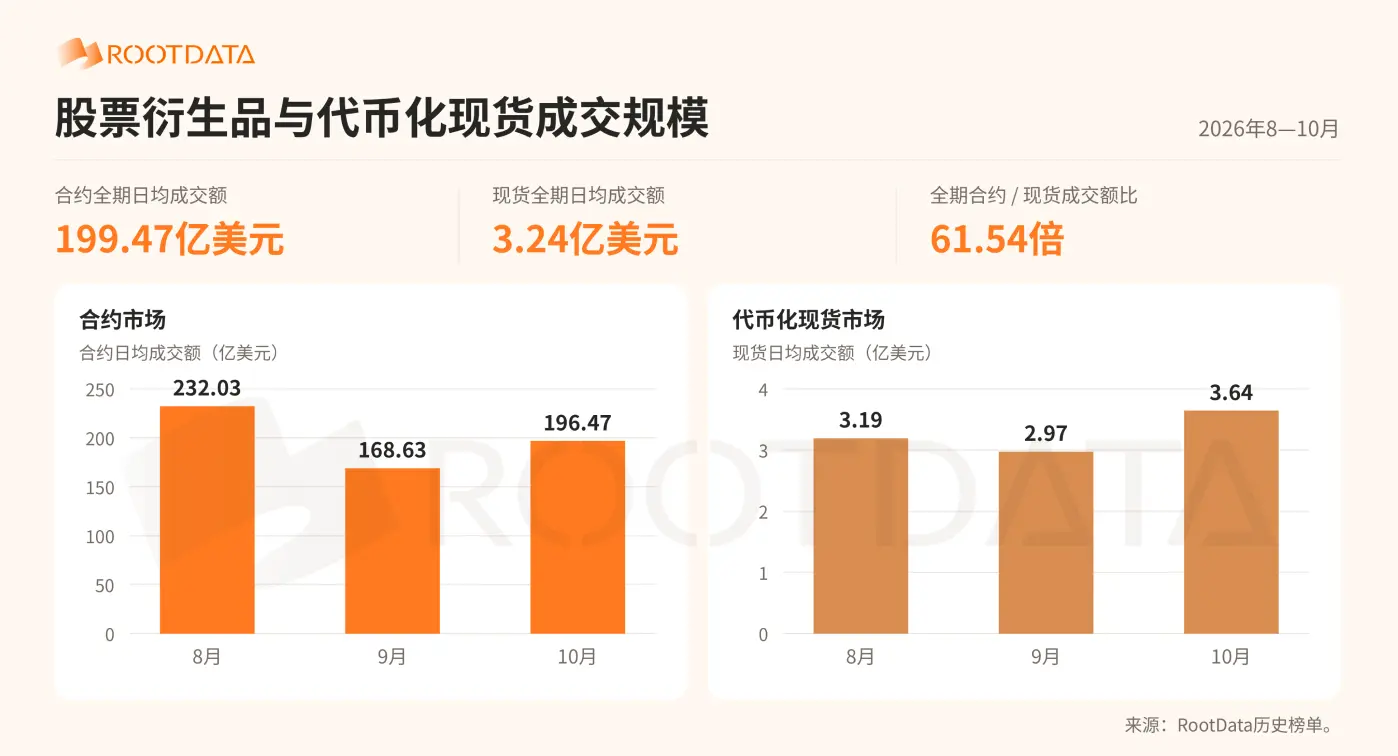
RootData reports $324 million in average daily tokenized-stock spot volume, versus $19.947 billion in average daily stock-derivatives volume for its comparison—about 61.5 times as much. Spot volume averaged $364 million in October, up 22.72% from September. The report’s issuer comparison covers Ondo, bStocks, xStocks, Reality and Robinhood Stock Tokens; it should not be mistaken for a direct comparison of identical exchange and issuer datasets.
In the issuer product data cited by RootData, Ondo, bStocks and xStocks had reported assets under management of $1.3 billion, $1.2 billion and $1.0 billion, respectively. Reality and Robinhood were listed at $161 million and $157 million. Reality had the broadest stated coverage, at more than 3,200 assets, and offered direct market access, request-for-quote execution and on-chain liquidity pools. RootData says Reality paid dividends to holders in stablecoins, whereas the other four products automatically reinvested after-tax dividends. It also says Reality listed an independent third-party CPA reserve attestation; that description is not an independent assessment of the attestation’s scope.
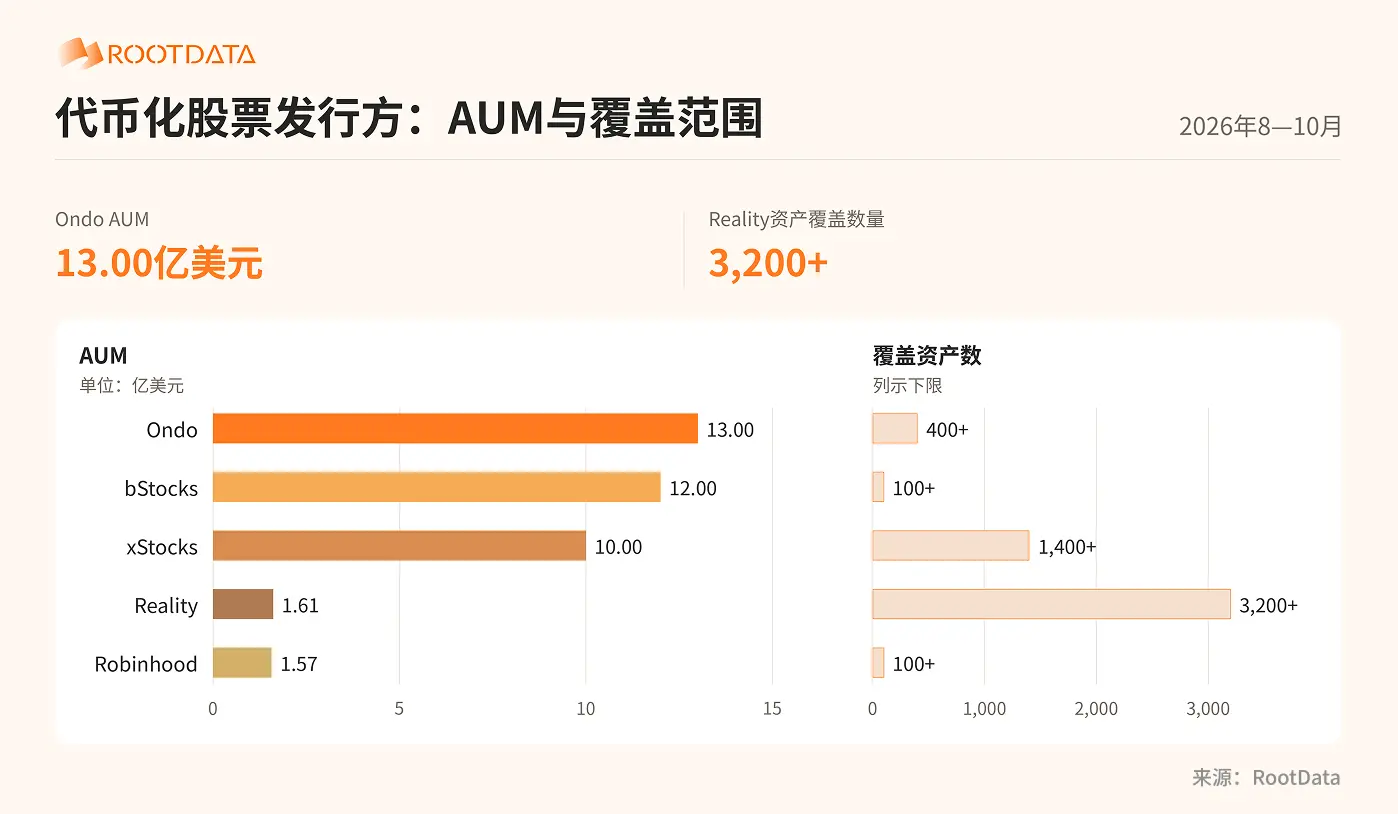
The research question is whether product breadth and displayed liquidity translate into sustained trading and holdings. RootData presents that conversion as unresolved, particularly for Reality’s broad catalog and for exchanges expanding contract listings.
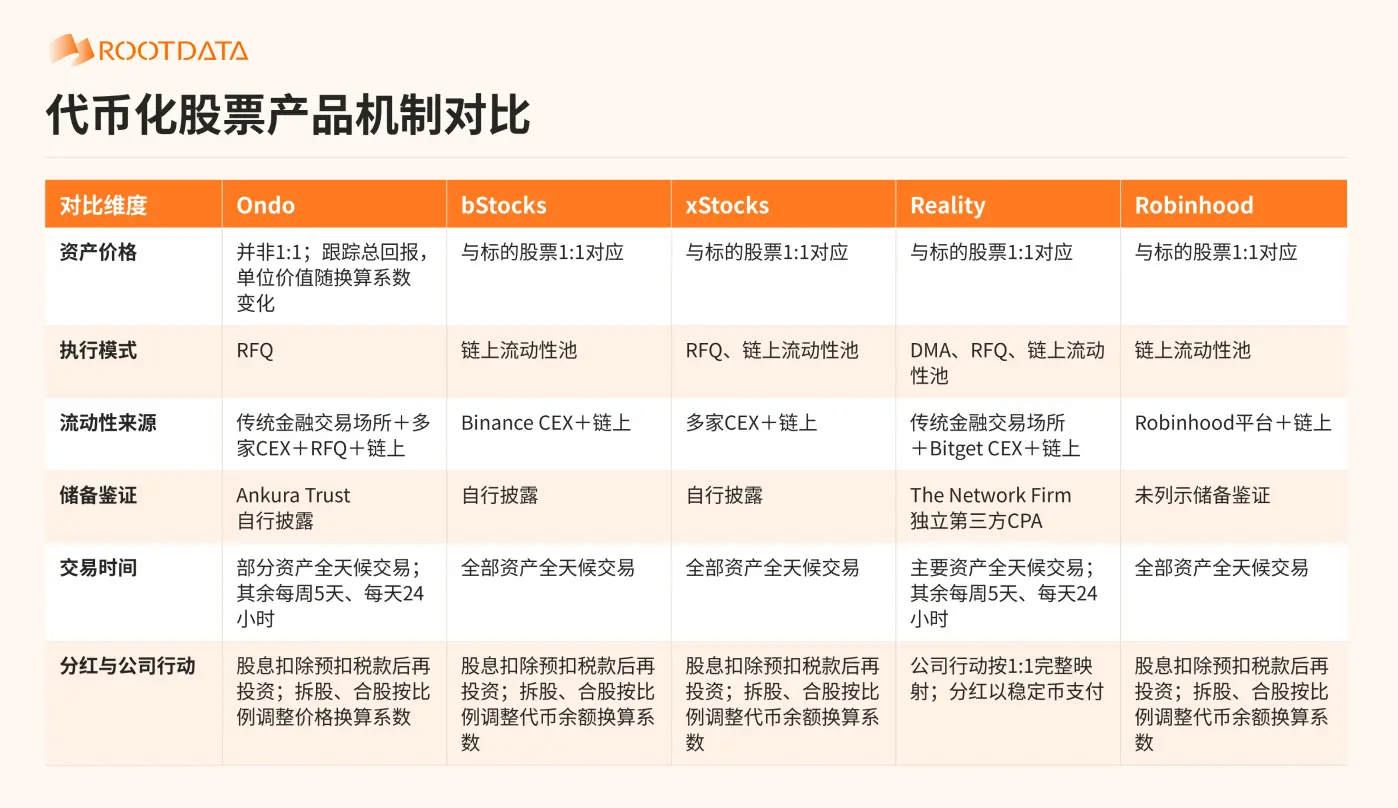
Methodology and limits: RootData attributes its figures to its contract and spot rankings and historical snapshots. It calculates platform averages over days with valid observations rather than filling missing dates with zero; cross-platform averages are sums of platform averages. Daily volume uses a rolling 24-hour figure, and rounding may produce small discrepancies. These choices matter when comparing the reported aggregates or attempting to reproduce them.