As reported on November 13, 2026, Index Industries was preparing a tokenized product intended to give holders exposure to an index of US home prices without owning property. The central question is whether a daily index, a reserve-backed token and institutional liquidity arrangements can make that exposure tradable and redeemable at scale.
The company announced a $50 million seed round on November 10, led by Lightspeed Venture Partners, with participation from Polychain Capital, Galaxy Ventures and Wintermute Ventures. It was co-founded by Josh Rosenthal, a former president and general partner at Polychain Capital, and Brian Hardecker, founder and CEO of residential real-estate platform Longmark.
From housing data to a daily index
The size of the underlying market depends on what is measured. According to the Federal Reserve’s financial accounts for the second quarter of 2026, owner-occupied US housing was worth $49.8 trillion and homeowners’ equity was about $35.8 trillion. Index Industries estimated the broader US residential property market at $55 trillion. Those figures use different scopes and should not be treated as interchangeable.
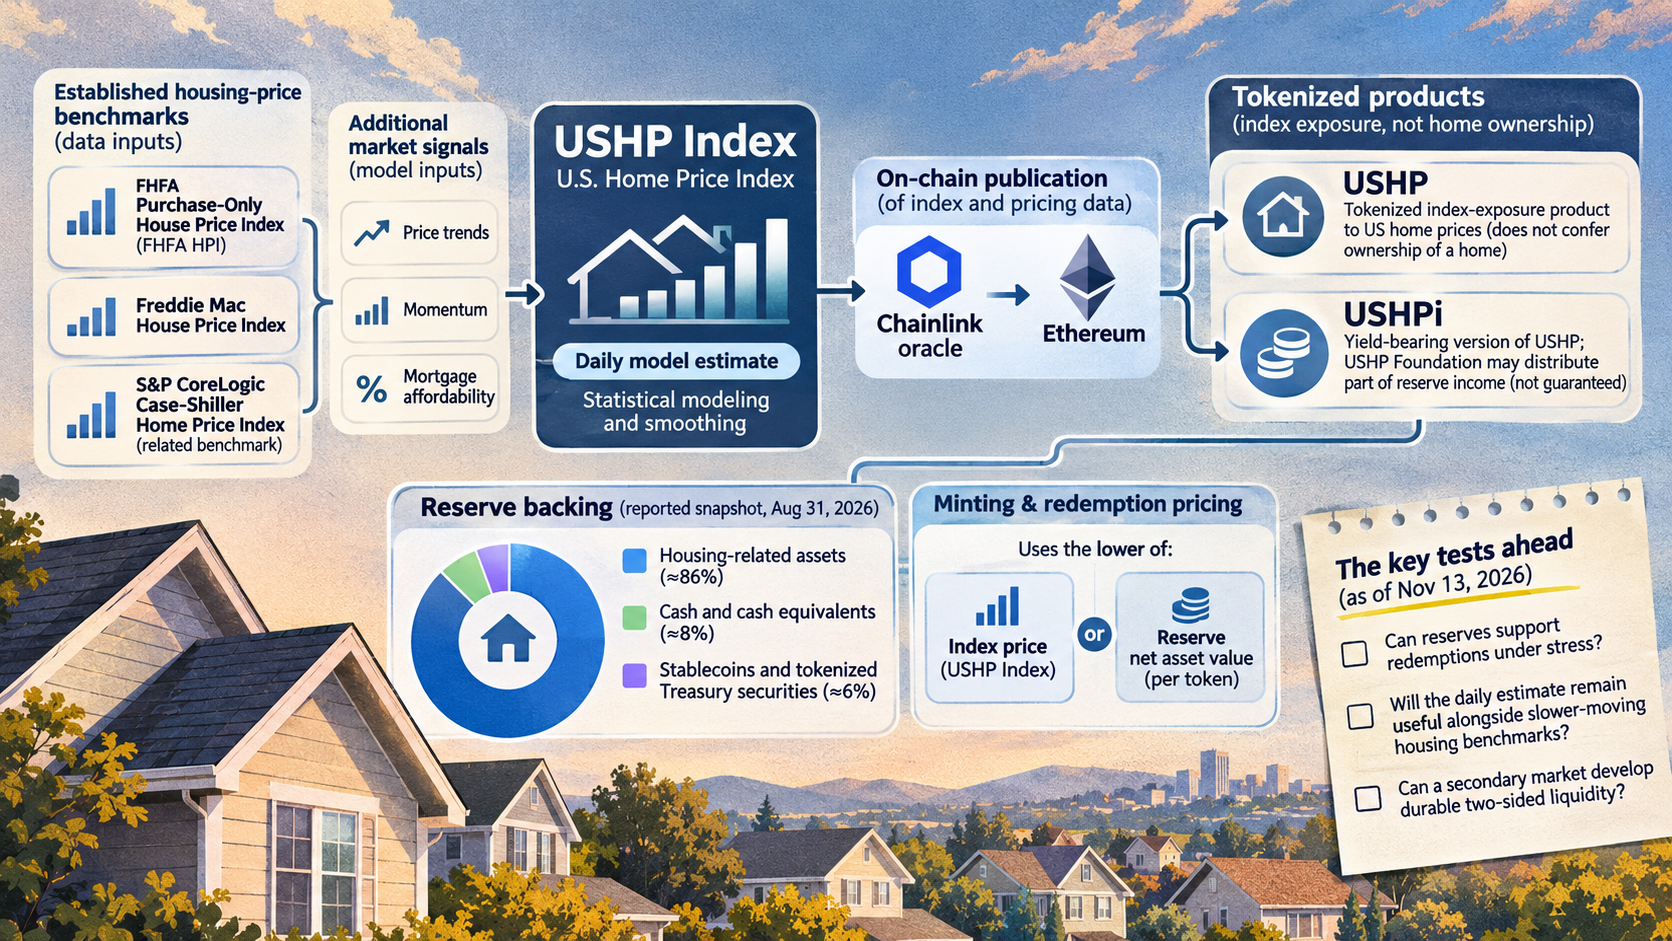
Existing benchmarks, including the Federal Housing Finance Agency’s House Price Index and the S&P CoreLogic Case-Shiller Home Price Index, provide housing-price measurements but are not themselves products an investor can buy. Index Industries’ proposed benchmark, the USHP Index, is intended to produce a daily national price estimate. Its stated methodology starts with established measures including the FHFA Purchase-Only HPI and the Freddie Mac House Price Index, then uses statistical smoothing and signals such as price trends, momentum and mortgage affordability.
The index has operated in real time since March 2026, according to the original report; earlier values are backtested or hypothetical. The company says mortgage and housing-data firm Andrew Davidson & Co independently reviewed its methodology. That reported review does not, by itself, establish how accurately a daily estimate will track subsequently observed housing prices.
Index values and related pricing data are published to Ethereum through Chainlink oracles for use in the product’s issuance, minting and redemption process. That on-chain publication distributes a model-derived price; it does not turn infrequently traded homes into continuously observed assets.
What a USHP holder owns—and how an exit is priced
USHP is a tokenized index-exposure product issued by USHP Limited and supported by housing-related reserves. It does not confer ownership of a home or a fraction of one. A second product, USHPi, is designed to let holders convert USHP into a yield-bearing version; the USHP Foundation may distribute to USHPi holders part of the income generated by reserve assets. That is a product design, not a guaranteed distribution.
The reserve mix matters because USHP does not price minting and redemption solely against the housing index. It uses the lower of the index price and the reserve net asset value attributable to each token. If the index rises but reserve value does not keep pace, redemption is priced at the lower reserve value. This constrains payment above the value of the backing assets, but it also means an exit need not capture the index’s full reported gain.
USHP’s website reported that, in an August 31, 2026 reserve snapshot, approximately 86% of reserves were housing-related assets, 8% cash and cash equivalents, and 6% stablecoins and tokenized Treasury securities. Those proportions describe the reported composition on that date, not how quickly the assets could be converted to cash during heavy redemptions.
The test left by earlier housing-index futures
USHP is not the first attempt to make housing prices tradable without transferring homes. CME launched cash-settled futures and options based on S&P/Case-Shiller indexes in May 2006. The original report cited 2,935 real-estate futures contracts traded during 2007, against 2.2 billion contracts across CME’s futures markets. In the first nine months of 2008, average trading volume in the real-estate futures fell 59% year over year and average open interest fell 70%.
Those contracts differ from a reserve-backed token that can be minted and redeemed. Still, the earlier market illustrates a relevant constraint: homes trade slowly, local property prices can diverge from a national index, and prospective hedgers do not necessarily need to trade in matching sizes, directions or time frames. A new settlement mechanism alone cannot ensure persistent counterparties.
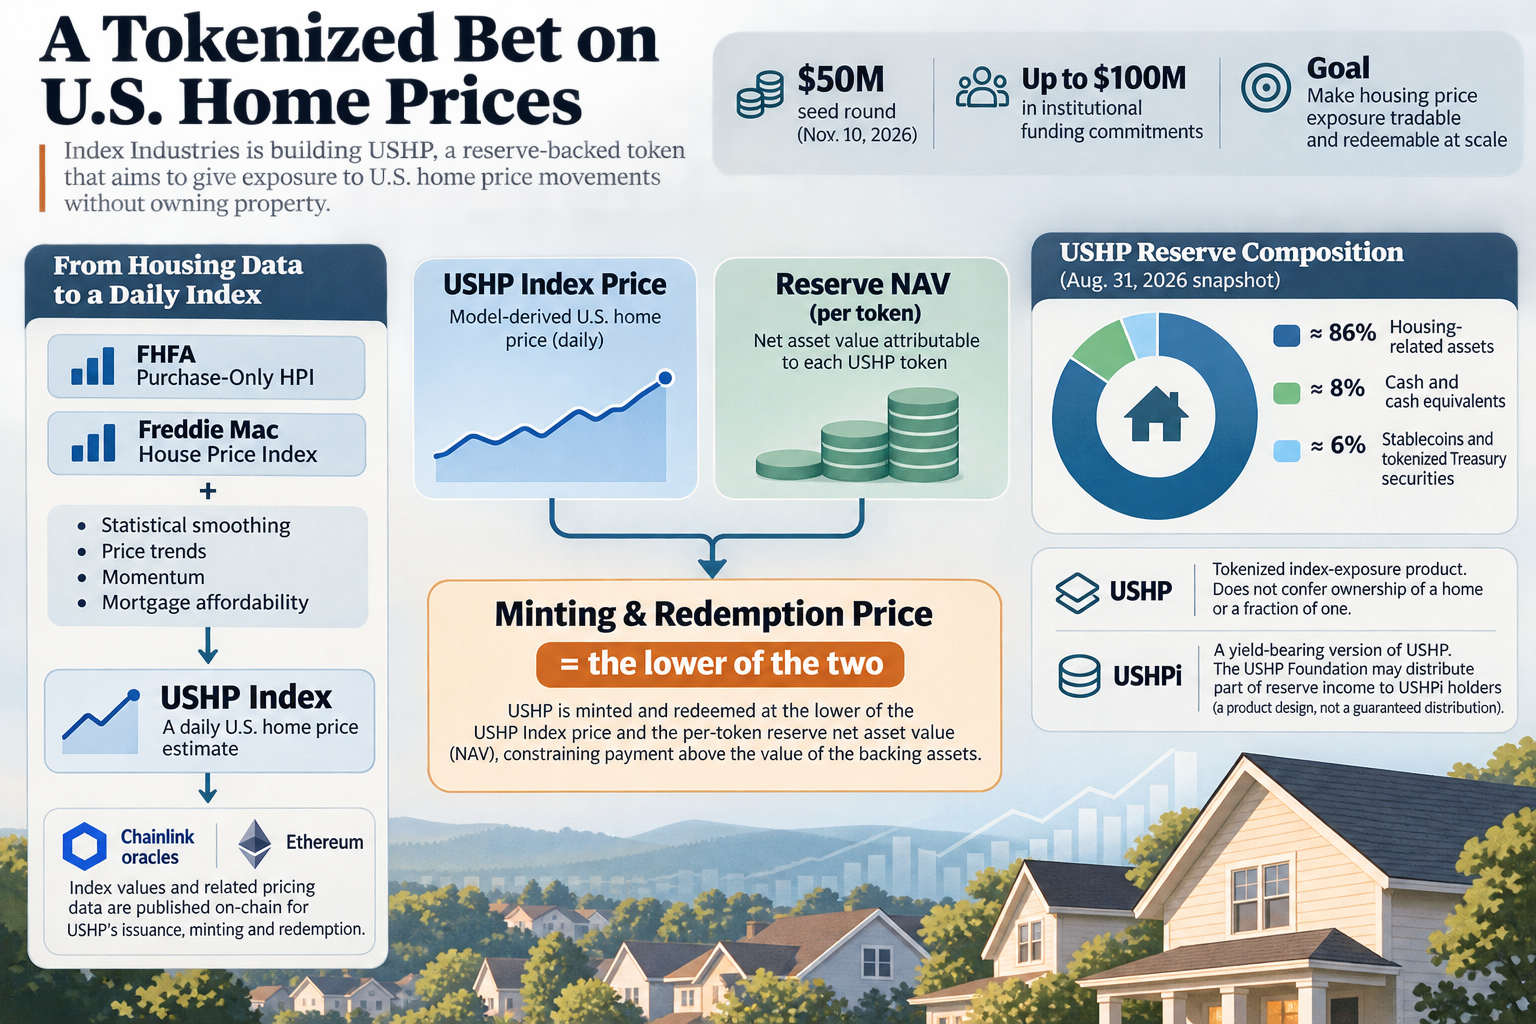
Index Industries’ planned response includes a dedicated liquidity reserve, institutional participation and potential uses in lending markets, yield protocols and trading venues. Before launch, USHP had obtained commitments of up to $100 million in institutional funding, according to the report. Galaxy and its affiliates were expected to act as institutional minters and liquidity providers, while Forward Industries committed up to $50 million. These are commitments and intended roles, not evidence of sustained trading depth. The proposed integrations likewise should not be mistaken for established demand.
USHP’s distinguishing test is therefore observable rather than conceptual: whether its housing-related reserves can support redemptions under stress, whether its daily estimate remains useful alongside slower-moving housing benchmarks, and whether a secondary market develops durable two-sided liquidity. As of the November 13, 2026 report, those outcomes remained unproven.