Historical report: BlockBeats published the underlying account on November 11, 2026, at 12:03 p.m. UTC+8. The figures and expected filing date below reflect that reporting period, not current prices or developments.
StablecoinX, a Nasdaq-listed digital-asset treasury company trading as USDE, held approximately 3.029 billion ENA tokens—about 20% of the token supply—according to investment firm Starkiller Capital. Starkiller’s research argued that the stock traded at a steep discount to the market value of those holdings after restrictions on the tokens were lifted. Starkiller also disclosed that it held the trade it was advocating, giving it a direct interest in a narrower discount.
What the discount measures
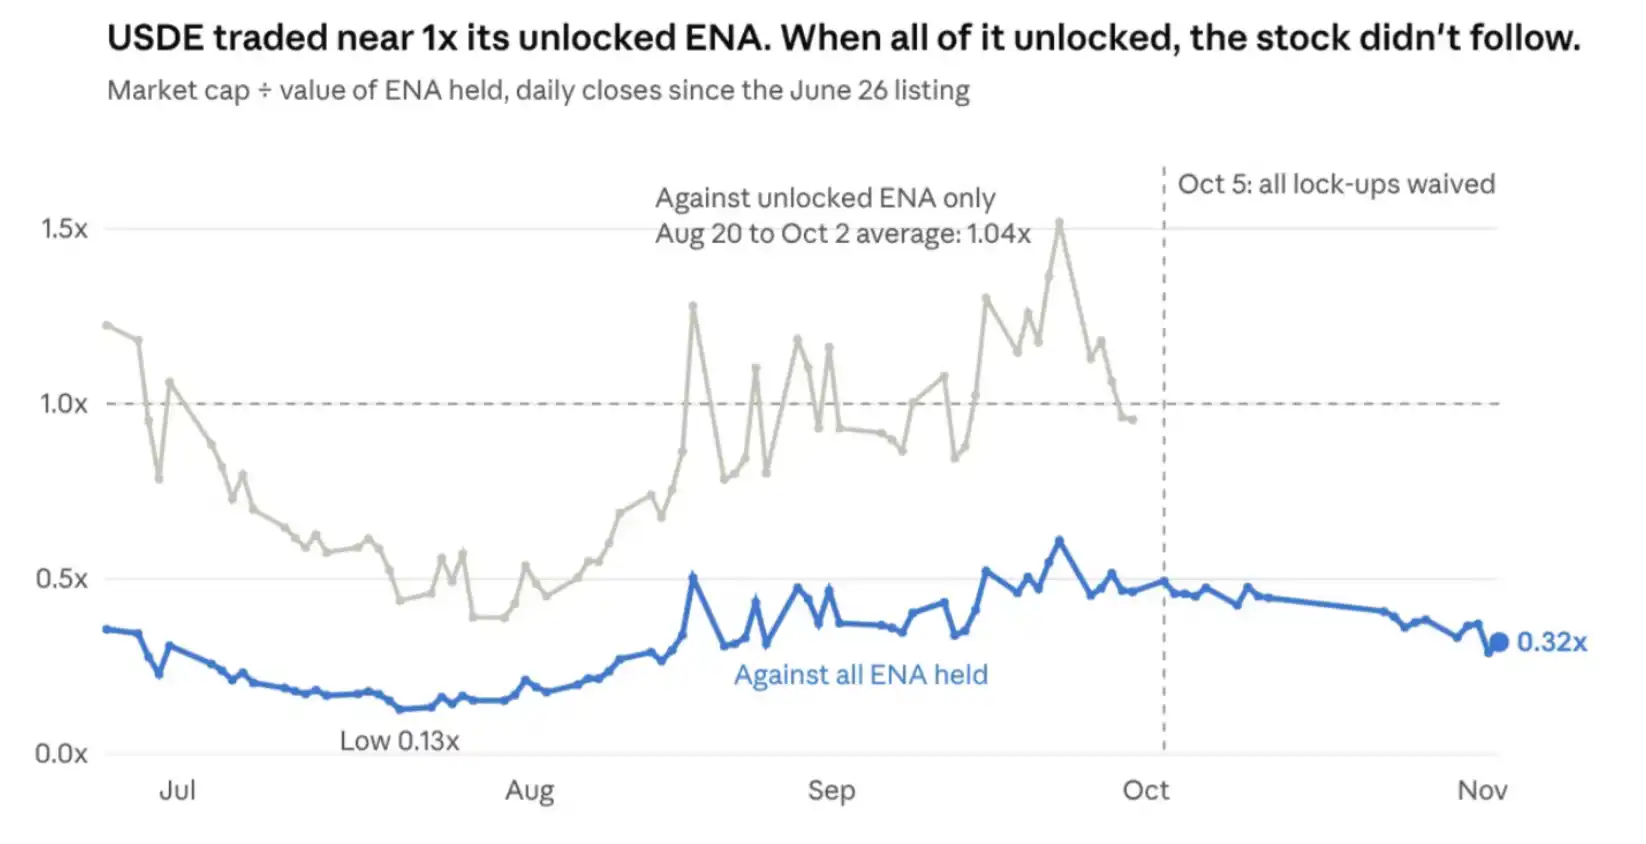
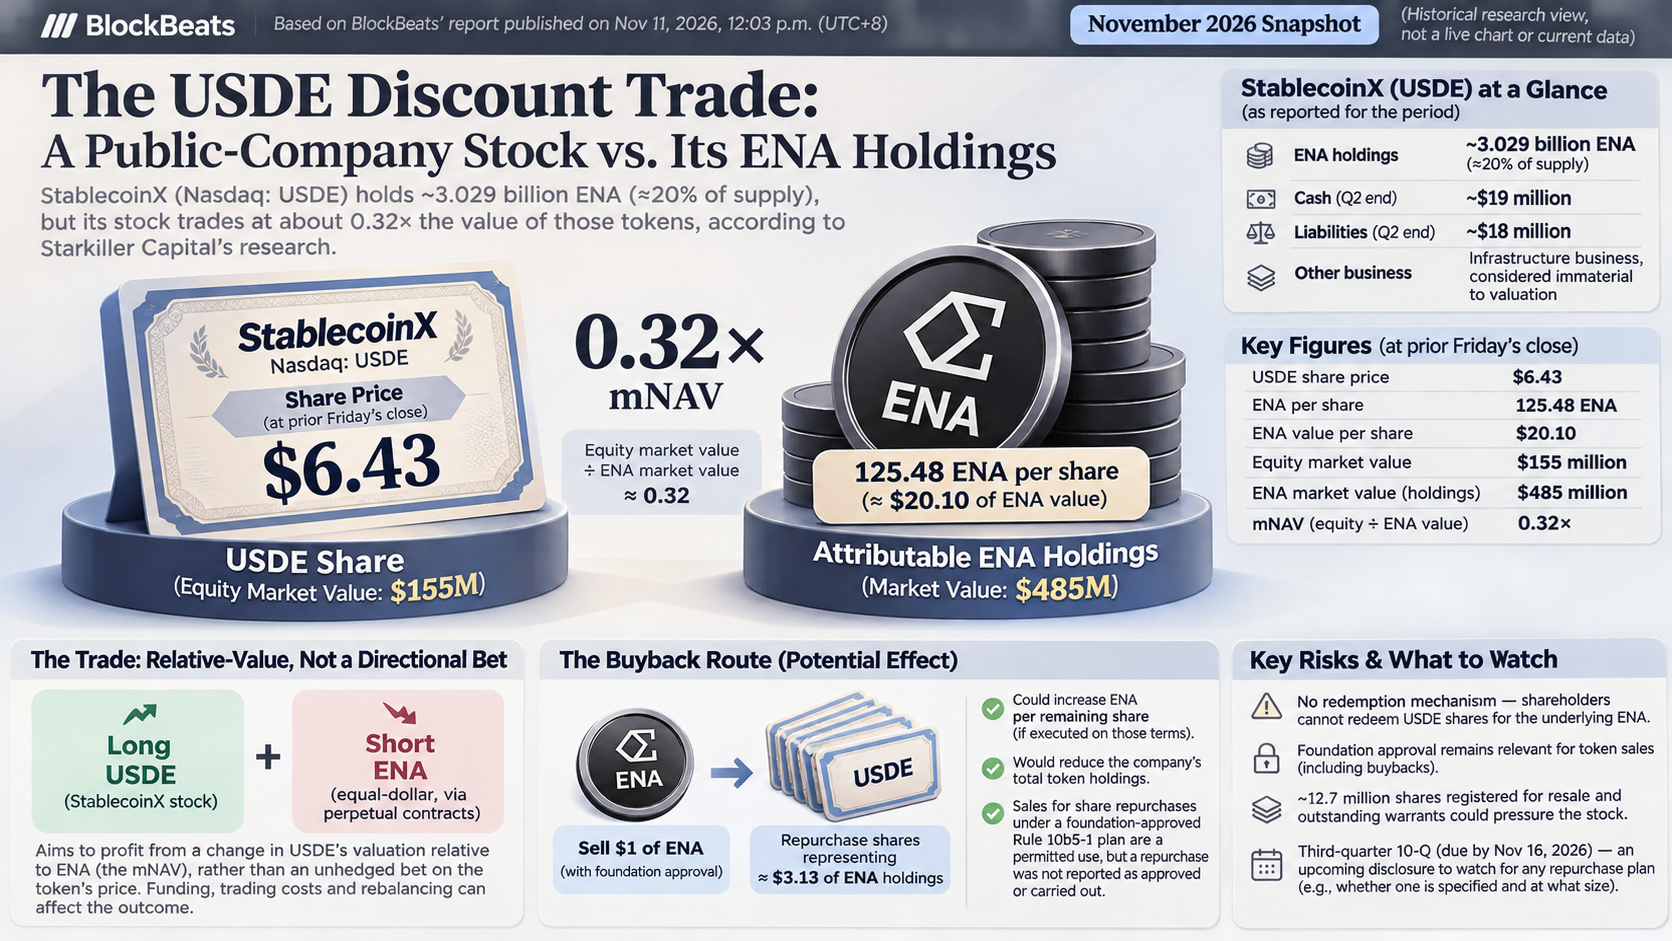
At the previous Friday’s close, Starkiller put USDE at $6.43 per share, against 125.48 ENA per share worth $20.10. That made the share price approximately 0.32 times the indicated ENA value per share. Starkiller described the same comparison as a $155 million equity market value against $485 million of tokens.
This mNAV measure divides equity market value by the market value of the company’s ENA; it is not a redemption price or a full accounting valuation. StablecoinX also had an infrastructure business, which Starkiller considered immaterial to its valuation. The source reported approximately $19 million in cash and $18 million in liabilities at the end of the second quarter.
The unlock and the proposed route to buybacks
The original token agreement had scheduled roughly half of StablecoinX’s ENA to unlock gradually over 48 months, with sales also subject to Ethena Foundation consent. According to the account, Ethena and the foundation signed a waiver on September 14 that lifted the lockup restrictions effective October 5. Sales still required foundation approval. The waiver identified sales to fund share repurchases under a foundation-approved Rule 10b5-1 plan as a permitted use; it did not establish that a repurchase had been approved or carried out.
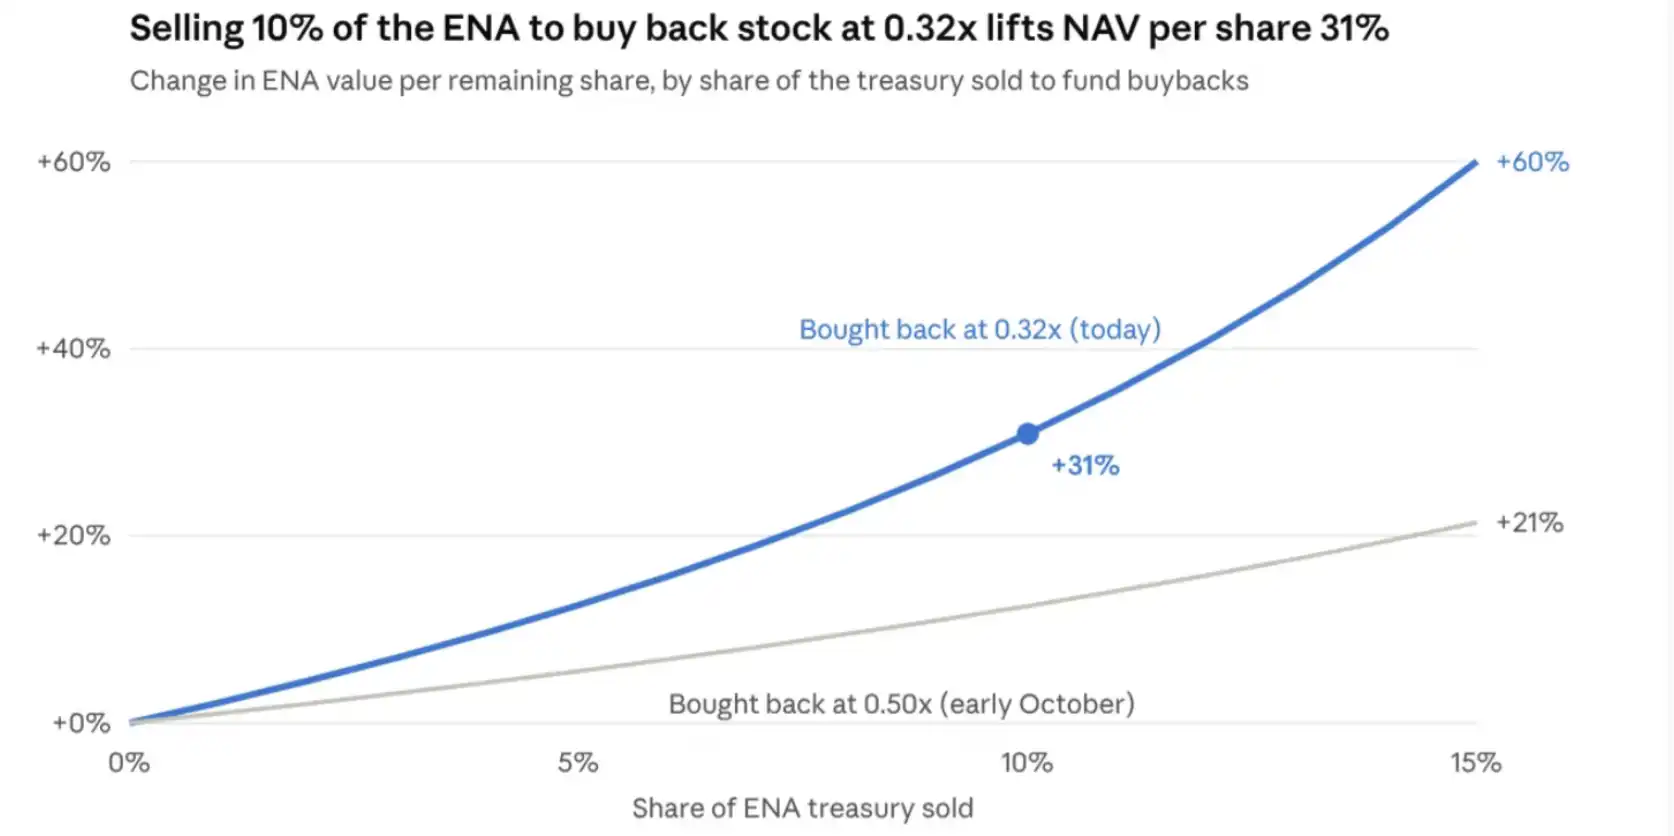
Starkiller’s arithmetic illustrates the potential effect. At 0.32 times ENA value, selling $1 of ENA to repurchase shares could retire shares representing approximately $3.13 of ENA holdings at the prevailing valuation. That would increase ENA per remaining share if the transactions occurred on those terms. It would also reduce the company’s total token holdings. The foundation had a right to buy ENA the company proposed to sell, but the source did not establish that it would do so.
The trade—and its unresolved assumptions
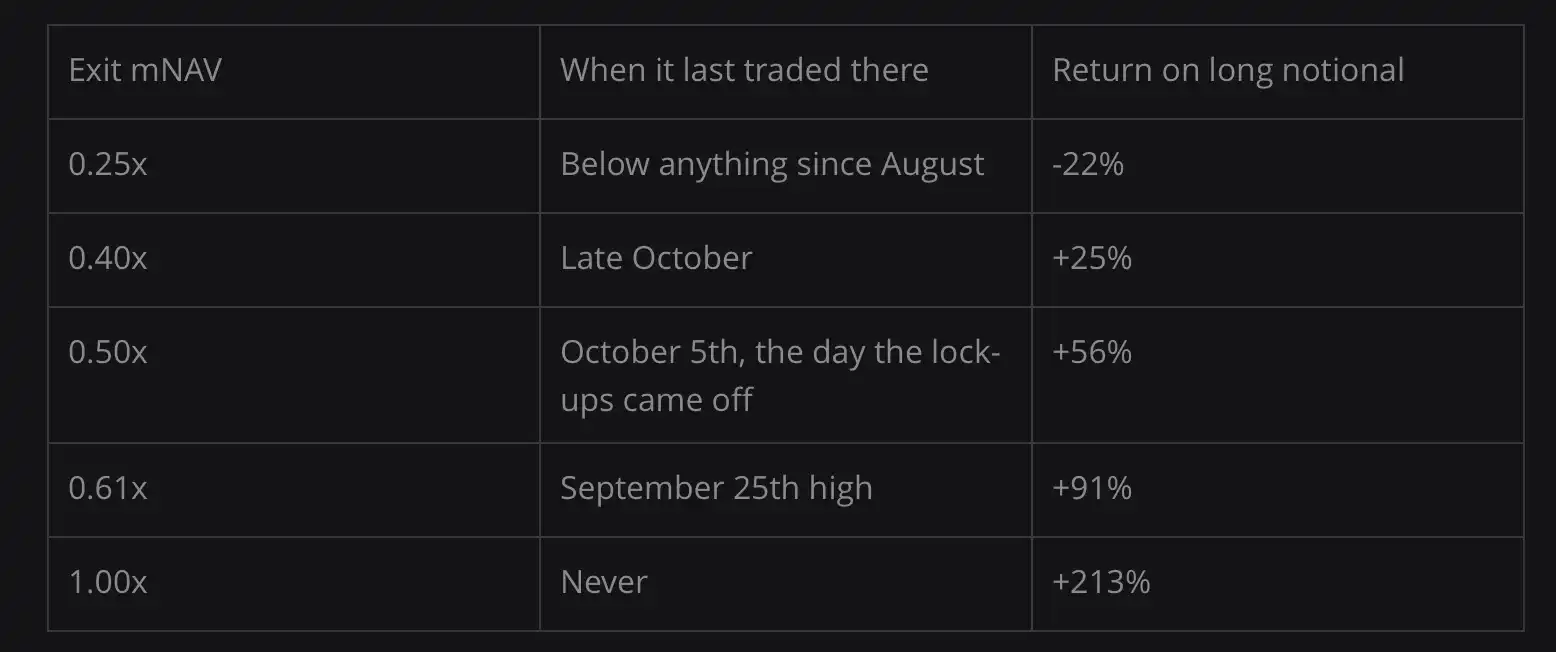
Starkiller said it first bought USDE in August at an mNAV of about 0.18, took profit on its accumulated shares near 0.60, and subsequently rebuilt a larger position as the multiple fell. Its described trade paired a long USDE position with an equal-dollar short in ENA, using perpetual contracts for the short. The intended exposure was to a change in the stock’s valuation relative to ENA, rather than an unhedged bet on the token price. Funding, trading costs and the need to rebalance could change the outcome.
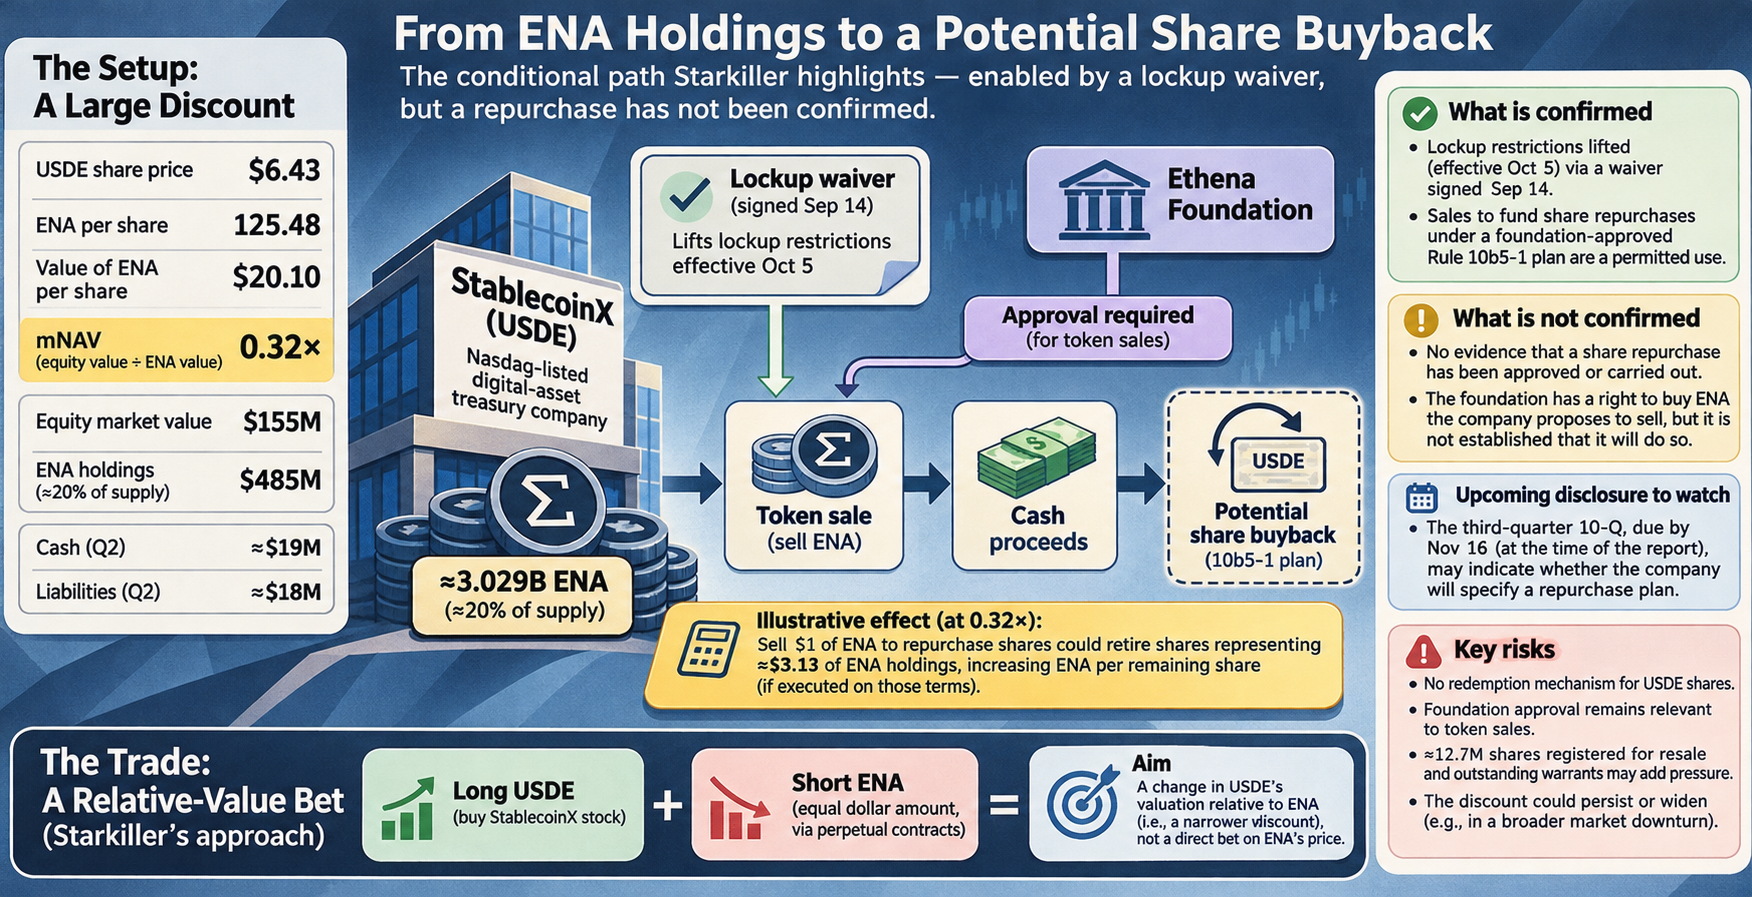
A narrower discount is not guaranteed. Shareholders had no mechanism to redeem USDE shares for the underlying tokens, and foundation approval remained relevant to token sales. The source also identified approximately 12.7 million shares registered for resale and outstanding warrants as potential pressures on the stock. Starkiller expected the third-quarter 10-Q, due by November 16 at the time of its research, to offer a chance to assess whether the company would specify a repurchase plan. That was an upcoming disclosure to watch, not evidence that a buyback was underway.
Source: theblockbeats.info (originally published 2026-11-11 12:03 UTC+8)